Unlocking Growth: 3 Financing Options for Front Door Refinishing Companies

front door refinishers near me


Front door refinishing companies play a vital role in enhancing the curb appeal and overall aesthetic of homes and businesses. As demand for such services continues to rise, many of these businesses find themselves in a position where expansion becomes not just desirable but necessary to meet the growing market demand. However, expansion requires capital, and securing financing can sometimes pose a challenge for small to medium-sized businesses. In this article, we will explore three viable financing options that front door refinishing companies can consider to expand their operations and thrive in a competitive market.

Traditional Bank Loans

One of the most common ways for businesses to secure financing for expansion is through traditional bank loans. Banks offer a variety of loan products tailored to the needs of businesses, including term loans, lines of credit, and Small Business Administration (SBA) loans.

Term loans provide a lump sum of capital that is repaid over a fixed period with regular payments of principal and interest. These loans are suitable for financing large purchases such as equipment, vehicles, or property needed for expansion. On the other hand, lines of credit offer businesses access to a revolving credit line that can be drawn upon as needed. This flexibility can be advantageous for front door refinishing companies that may experience fluctuations in cash flow due to seasonality or other factors.

SBA loans, guaranteed by the U.S. Small Business Administration, are designed to support small businesses that may have difficulty qualifying for traditional bank financing. These loans typically offer favorable terms, including lower down payments and longer repayment terms, making them an attractive option for businesses looking to expand.

Equipment Financing

Front door refinishing companies rely on specialized equipment and tools to carry out their services efficiently and effectively. Equipment financing provides businesses with the capital needed to purchase or lease equipment without requiring a large upfront investment.

Equipment loans allow businesses to spread the cost of equipment purchases over time while retaining ownership of the equipment once the loan is repaid. Alternatively, equipment leasing offers businesses the flexibility to use equipment for a predetermined period in exchange for regular lease payments. At the end of the lease term, businesses may have the option to purchase the equipment at a reduced price, upgrade to newer equipment, or return the equipment.

By leveraging equipment financing, front door refinishing companies can acquire the tools and machinery necessary to expand their operations without putting strain on their cash flow.

Alternative Financing Options

In addition to traditional bank loans and equipment financing, front door refinishing companies may explore alternative financing options to fund their expansion efforts. These options include:

Invoice Financing: Front door refinishing companies often extend credit terms to customers, resulting in outstanding accounts receivable. Invoice financing allows businesses to access cash by selling their unpaid invoices to a third-party financing company at a discount. This provides immediate liquidity and helps improve cash flow, allowing companies to reinvest in their operations and fuel growth.

Peer-to-Peer Lending: Peer-to-peer lending platforms connect borrowers directly with individual investors willing to fund their loans. Front door refinishing companies can use these platforms to secure financing quickly and conveniently, bypassing the traditional banking system. Peer-to-peer lending offers flexible terms and competitive interest rates, making it an attractive option for businesses seeking alternative sources of capital.

Crowdfunding: Crowdfunding platforms enable businesses to raise capital by soliciting small contributions from a large number of individuals, typically through online campaigns. Front door refinishing companies can leverage crowdfunding to fund specific projects or initiatives, such as launching a new service or expanding into new geographic markets. By tapping into the collective power of the crowd, businesses can access capital while also generating buzz and awareness for their brand.

Conclusion

Expanding operations is an exciting but challenging endeavor for front door refinishing companies. By exploring a range of financing options, including traditional bank loans, equipment financing, and alternative financing solutions, businesses can access the capital needed to fuel growth and capitalize on market opportunities. Whether through securing a term loan to finance a new facility, leveraging equipment financing to upgrade machinery, or tapping into alternative sources of funding such as invoice financing or crowdfunding, front door refinishing companies can take strategic steps to expand their operations and achieve long-term success in a competitive market.

Unlocking Growth: 3 Ways a Dallas, TX Restaurant Design Company Can Flourish with a Business Loan

restaurant interior design


Dallas, TX, a city renowned for its vibrant culinary scene, is home to numerous restaurants striving to stand out amidst fierce competition. Behind every successful restaurant lies a well-thought-out design, carefully crafted to create an unforgettable dining experience. However, for restaurant design companies in Dallas, staying ahead in this dynamic industry requires not just creativity and skill, but also financial stability. In this blog post, we’ll explore how a restaurant design company in Dallas can leverage a business loan to fuel growth and thrive in the ever-evolving restaurant landscape.

Investing in Cutting-Edge Equipment and Technology

In the realm of restaurant design, staying up-to-date with the latest equipment and technology is crucial. Whether it’s state-of-the-art kitchen appliances, advanced design software, or innovative furniture materials, investing in the right tools can significantly enhance efficiency, creativity, and overall quality of work. However, acquiring such equipment often comes with a hefty price tag.

This is where a business loan can make a significant difference. By securing financing, a Dallas restaurant design company can afford to invest in cutting-edge equipment and technology without putting undue strain on their cash flow. With access to the latest tools, designers can streamline their processes, deliver superior results, and ultimately attract more clients. From high-efficiency kitchen appliances to virtual reality design software, the possibilities are endless, and a business loan can provide the necessary resources to turn these possibilities into realities.

Expanding Marketing and Outreach Efforts

In the competitive landscape of Dallas’s restaurant industry, visibility is key. For a restaurant design company, effective marketing and outreach are essential for attracting new clients and building lasting relationships within the industry. However, executing a comprehensive marketing strategy often requires substantial financial resources, including funds for advertising campaigns, website development, and networking events.

By securing a business loan, a Dallas restaurant design company can expand its marketing and outreach efforts with confidence. Whether it’s investing in targeted digital advertising, attending industry trade shows, or revamping their website for better online visibility, a business loan can provide the necessary capital to reach a broader audience and showcase the company’s unique design offerings. With increased visibility and a strong marketing presence, the company can attract more clients, secure larger projects, and ultimately drive growth and profitability.

Scaling Operations and Talent Acquisition

As demand for their services grows, Dallas restaurant design companies may find themselves needing to scale their operations and expand their team to meet client expectations effectively. However, scaling a business requires careful planning and sufficient resources, particularly when it comes to hiring skilled professionals and expanding infrastructure.

A business loan can provide the financial foundation needed to scale operations and acquire top talent. Whether it’s hiring additional designers, project managers, or administrative staff, having access to capital can enable the company to build a strong team capable of delivering exceptional results. Furthermore, the loan can also be used to invest in expanding office space, upgrading technology infrastructure, or implementing efficient project management systems, all of which are essential for supporting growth and maintaining high-quality standards.

Conclusion

In the bustling city of Dallas, TX, restaurant design companies play a vital role in shaping the culinary landscape and creating memorable dining experiences. However, achieving success in this competitive industry requires more than just talent and creativity—it also demands financial stability and strategic investment. By leveraging a business loan, restaurant design Dallas companies can unlock new opportunities for growth, whether through investing in cutting-edge equipment and technology, expanding marketing efforts, or scaling operations and talent acquisition. With the right financial resources at their disposal, these companies can thrive in the ever-evolving restaurant landscape and continue to leave their mark on the vibrant Dallas dining scene.

Understanding the Impact of Car Appraisal on Financing: A Comprehensive Guide

classic car appraisers near me


In the realm of purchasing a vehicle, the process of financing often plays a crucial role. Whether you’re buying a brand new car or opting for a used one, understanding how a car’s appraisal affects financing is essential. Far from being a mere formality, the appraisal process can significantly influence the terms and conditions of your loan. In this comprehensive guide, we’ll delve into the intricate relationship between car appraisal and financing, shedding light on its importance and implications.

The Significance of Car Appraisal

Definition and Purpose: A car appraisal involves evaluating the value of a vehicle based on various factors such as its condition, mileage, age, and market demand. This process serves multiple purposes, including determining the fair market value of the car, assessing its condition for insurance purposes, and crucially, influencing financing decisions.

Types of Appraisals: There are different types of appraisals, ranging from informal assessments by dealerships to formal evaluations conducted by certified appraisers. Each type serves a specific purpose and can impact financing differently.

Impact on Loan Approval

Loan-to-Value Ratio (LTV): One of the primary ways in which car appraisal affects financing is through the loan-to-value ratio. LTV represents the ratio of the loan amount to the appraised value of the car. A higher LTV indicates a riskier loan for the lender, potentially resulting in higher interest rates or stricter lending criteria.

Collateral for the Loan: In auto financing, the vehicle itself serves as collateral for the loan. A higher appraised value provides the lender with greater assurance of recovering their funds in case of default. Consequently, a favorable appraisal can lead to more lenient lending terms.

Influence on Interest Rates

Creditworthiness and Appraisal: While credit score remains a crucial factor in determining interest rates, the appraised value of the car can also influence the rate offered by lenders. A higher appraised value may result in a lower interest rate, as it reduces the lender’s perceived risk.

Negotiating Power: Armed with a favorable car appraisal, borrowers may have more leverage in negotiating interest rates with lenders. A well-appraised vehicle can demonstrate financial stability and responsibility, strengthening the borrower’s position.

Role in Down Payments and Terms

Down Payment Requirements: Lenders often require a down payment as a percentage of the car’s purchase price. The appraised value of the vehicle can affect the minimum down payment amount, with a higher value potentially reducing the upfront payment required.

Loan Terms: The appraisal can also impact the terms of the loan, including the repayment period and monthly installments. A higher appraised value may allow borrowers to qualify for longer loan terms or lower monthly payments, enhancing affordability.

Strategies for Maximizing Appraisal Value

Maintenance and Repairs: Regular maintenance and addressing any issues can improve the overall condition of the vehicle, leading to a higher appraisal value.

Presentation: Presenting the vehicle in its best possible condition during the appraisal process can positively influence the appraiser’s assessment.

Documentation: Providing comprehensive documentation, such as service records and vehicle history reports, can substantiate the car’s value and condition.

Conclusion

In the world of auto financing, the car appraisal near me holds significant sway over the terms and conditions of a loan. From influencing interest rates to determining down payment requirements, the appraised value plays a pivotal role in shaping the financing process. As such, borrowers should strive to maximize the value of their vehicle through diligent maintenance, proper presentation, and thorough documentation. By understanding the intricacies of car appraisal and its impact on financing, individuals can make informed decisions and secure favorable loan terms for their automotive endeavors.


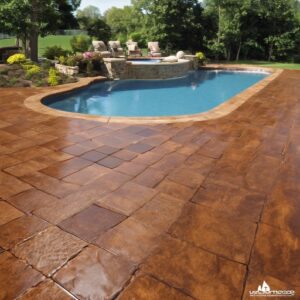
Unlocking Financing Options for Resurfacing Your Pool Deck in Orlando, FL

pool deck resurfacing near me


Are you a proud pool owner in sunny Orlando, Florida, looking to revamp your outdoor oasis? One of the most effective ways to breathe new life into your pool area is by resurfacing your pool deck. However, undertaking such a project can come with a significant financial investment. Fear not, as there are various financing options available to help you achieve the pool deck of your dreams without breaking the bank. In this comprehensive guide, we’ll explore the ins and outs of financing options specifically tailored for resurfacing pool decks in Orlando, FL.

Assessing Your Budget and Needs

Before diving into financing options, it’s crucial to assess your budget and determine the scope of your project. Take into account factors such as the size of your pool deck, desired materials, and any additional features you wish to incorporate. This initial assessment will help you establish a realistic budget and guide your financing decisions.

Research Local Lenders and Financing Programs

Orlando, FL, boasts a vibrant community of local lenders and financing programs specializing in home improvement projects, including pool deck resurfacing. Start by researching banks, credit unions, and online lenders in the Orlando area that offer loans tailored to home renovations. Additionally, inquire about any government-backed financing programs or grants available for homeowners undertaking energy-efficient upgrades, as some pool deck materials may qualify.

Home Equity Loans and Lines of Credit

If you have substantial equity in your home, leveraging it through a home equity loan or line of credit (HELOC) can be an attractive financing option for your pool deck resurfacing project. Home equity loans typically offer fixed interest rates and lump-sum payments, while HELOCs provide a revolving line of credit with variable interest rates. Consider consulting with a financial advisor to determine which option aligns best with your financial goals and circumstances.

Personal Loans

Personal loans are unsecured loans that can be used for various purposes, including home renovations. They offer flexibility in terms of loan amounts and repayment terms, making them a viable option for financing pool deck resurfacing projects. Compare interest rates and terms from multiple lenders to secure the most favorable loan terms for your needs.

Manufacturer or Contractor Financing

Some pool deck resurfacing companies in Orlando may offer financing options in partnership with manufacturers or financial institutions. These financing programs often come with competitive interest rates and convenient repayment plans tailored to the specific needs of the project. Be sure to inquire with your chosen contractor about any financing options they may offer and carefully review the terms and conditions before committing.

Energy-Efficiency Financing Program

In pursuit of sustainable and energy-efficient solutions, many homeowners in Orlando may qualify for financing programs aimed at promoting eco-friendly home improvements. Explore options such as Property Assessed Clean Energy (PACE) financing, which allows homeowners to finance energy-efficient upgrades, including pool deck resurfacing, through assessments on their property tax bills. These programs may offer attractive terms and repayment structures, making them worth considering for your project.

Credit Cards and Retail Financing

While not always the most cost-effective option, using credit cards or retail financing plans to fund your pool deck resurfacing project can provide convenience and flexibility, particularly for smaller-scale renovations. Be mindful of high-interest rates and fees associated with credit cards and retail financing, and aim to pay off the balance as quickly as possible to avoid accruing excessive interest charges.

Conclusion

Resurface pool deck Orlando can enhance the aesthetics, functionality, and value of your outdoor space, creating a haven for relaxation and entertainment. While the upfront cost of such a project may seem daunting, numerous financing options are available to help you bring your vision to life without straining your finances. Whether you opt for a home equity loan, personal loan, or energy-efficiency financing program, careful research and planning will empower you to make informed decisions and achieve the pool deck of your dreams. So, dive into the world of financing options and embark on your journey to transform your pool deck into a true oasis in the heart of Orlando.

Navigating the Financial Landscape: Securing a Loan for Your Articulation Assessment Speech Therapy Business

articulation assessments speech therapy


Embarking on the journey of establishing your own Articulation Assessment Speech Therapy business is an exciting venture. However, one of the critical aspects that entrepreneurs often grapple with is securing the necessary funds to kickstart or expand their enterprises. In this comprehensive guide, we’ll delve into the nuances of obtaining a loan for your speech therapy business, focusing on the specific needs and challenges associated with articulation assessment services.

Understanding the Financial Landscape

Assessing Your Funding Requirements

Before diving into the loan application process, it’s crucial to conduct a thorough assessment of your funding requirements. Consider factors such as facility setup, equipment procurement, licensing fees, and operational costs. This meticulous evaluation will provide a clear picture of the amount you need to borrow.

Creating a Detailed Business Plan

A well-crafted business plan serves as a roadmap for your enterprise and is a key document when seeking financing. Outline your business goals, target market, competitive landscape, and financial projections. Lenders often scrutinize business plans to gauge the viability of the venture and its potential for success.

Types of Loans Available

Small Business Administration (SBA) Loans

SBA loans are a popular choice for entrepreneurs as they offer favorable terms and lower interest rates. Understanding the SBA loan programs and eligibility criteria can significantly enhance your chances of approval. Explore options like the 7(a) Loan Program tailored for small businesses.

Traditional Bank Loans

Traditional bank loans remain a conventional method of securing business financing. However, they may require a solid credit history and collateral. Familiarize yourself with the application process, interest rates, and repayment terms associated with bank loans.

Alternative Financing Options

Explore alternative financing options such as online lenders, crowdfunding, and peer-to-peer lending platforms. While these avenues may have more flexible eligibility criteria, it’s essential to carefully review the terms and conditions to ensure they align with your business strategy.

Navigating the Loan Application Process

Organizing Your Financial Documents

Prepare a comprehensive set of financial documents, including income statements, balance sheets, tax returns, and cash flow projections. Lenders rely on these documents to assess your business’s financial health and repayment capability.

Building a Strong Credit Profile

A strong credit profile enhances your credibility as a borrower. Check your credit score and take proactive measures to address any issues. Lenders often use credit scores as a determining factor in loan approvals and interest rates.

Presenting a Compelling Loan Proposal

Craft a compelling loan proposal that clearly articulates your business’s purpose, funding requirements, and repayment plan. Highlight the unique value proposition of your articulation assessment speech therapy business and how the loan will contribute to its growth.

Conclusion

Securing a loan for your articulation assessment speech therapy business requires careful planning, a thorough understanding of available financing options, and a compelling loan application. By navigating the financial landscape strategically and presenting a robust case for your business, you can increase the likelihood of obtaining the funds needed to make your entrepreneurial dreams a reality. Remember, each step in the process plays a crucial role in positioning your business for success, so approach the journey with diligence and determination.

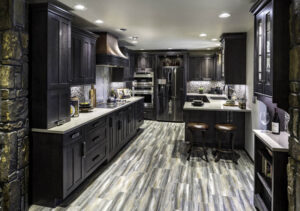
A Comprehensive Guide to Securing Financing for Kitchen Remodeling in Rancho Cucamonga, CA

kitchen remodeling California


Undertaking a kitchen remodeling project can breathe new life into your home, enhancing its aesthetics, functionality, and value. However, financing such renovations can often pose a significant challenge. Fortunately, several options exist for homeowners in Rancho Cucamonga, CA, seeking financial assistance to remodel their kitchens. In this comprehensive guide, we’ll explore various financing avenues, providing insights into loans, grants, and other resources available to residents embarking on a kitchen renovation journey in this vibrant city.

Assessing Your Budget and Needs

Before delving into financing options, it’s crucial to assess your budget and the scope of your kitchen remodeling project. Take inventory of the changes you wish to make, whether it involves updating appliances, replacing cabinets, or revamping the layout. Understanding your renovation needs and establishing a realistic budget will help guide your financing decisions.

Financing Options for Kitchen Remodeling

Personal Savings: Utilizing personal savings is a straightforward and interest-free method to fund a kitchen renovation. Evaluate your savings and determine how much you can allocate towards the project without compromising your financial security.

Home Equity Loans or HELOCs (Home Equity Lines of Credit): These options leverage the equity in your home, allowing you to borrow against it. Home equity loans offer a lump sum with a fixed interest rate, while HELOCs provide a revolving line of credit. Both can be viable options for substantial renovation costs, offering competitive interest rates.

Personal Loans: For homeowners without substantial equity or those who prefer not to use it as collateral, personal loans are unsecured loans that can fund kitchen remodeling. These loans typically have higher interest rates than home equity options but may be more accessible.

Government Loans and Grants: Investigate government-backed loans or grants available for home improvements, such as those offered by the Federal Housing Administration (FHA) or programs specific to California residents. These programs often have specific eligibility criteria but can provide financial assistance for qualifying projects.

Credit Cards: While not ideal for large-scale renovations due to higher interest rates, credit cards can be used for smaller kitchen updates or as a temporary financing solution. Some credit cards offer introductory periods with low or no interest, providing short-term funding flexibility.

Researching Local Resources and Assistance Programs:

Local Banks and Credit Unions: Explore lending options provided by local financial institutions in Rancho Cucamonga. They may offer personalized loan packages or special rates for homeowners seeking to remodel their kitchens.

Nonprofit Organizations: Some nonprofits or community organizations might offer financial assistance or resources for home improvements. Research local nonprofits dedicated to housing or community development that may provide grants or low-interest loans.

Tips for a Successful Financing Journey:

Compare Lenders and Loan Terms: Obtain quotes from multiple lenders, comparing interest rates, repayment terms, and associated fees to secure the most favorable financing option.

Review Eligibility Requirements: Understand the eligibility criteria for loans, grants, or assistance programs to ensure you meet the necessary qualifications before applying.

Create a Detailed Budget and Plan: Develop a comprehensive budget outlining all projected costs for the remodeling project to accurately estimate the required financing.

Conclusion

Embarking on a kitchen remodeling Rancho Cucamonga CA, necessitates careful financial planning and exploration of available financing options. By assessing your budget, researching various loan avenues, and considering local resources, homeowners can find suitable financial assistance to bring their kitchen renovation dreams to fruition. Remember to compare options, review eligibility requirements, and create a detailed plan to streamline the financing process and embark on a successful remodeling journey.

In closing, a well-thought-out financial strategy combined with a clear vision for your kitchen remodel will pave the way for a transformed, functional, and aesthetically pleasing culinary space in your Rancho Cucamonga home.

The Dragon’s Influence: How China Affects the US Economy

How China Affects US economy according to Chinese Translation Services


In today’s interconnected world, the global economy is a complex web of interdependencies. Among the many players in this economic arena, China stands out as a colossal force that significantly affects the United States’ economic landscape. As the world’s most populous country and the second-largest economy, China’s economic policies, trade practices, and financial maneuvers have profound implications for the United States. In this comprehensive blog post, we will explore the multifaceted ways in which China affects the US economy and why it matters.

Trade Relations

China is the United States’ largest trading partner, and the economic ties between these two giants are extensive. The trade relationship is often a subject of both praise and contention. Let’s delve into the key aspects of this intricate relationship:

Trade Deficit

One of the most significant aspects of China’s influence on the US economy is the trade deficit. The US consistently imports more goods from China than it exports, resulting in a trade deficit. This deficit can strain domestic industries, lead to job displacement, and impact the overall balance of trade. Critics argue that the trade deficit weakens the US economy, while proponents emphasize the benefits of access to affordable goods for American consumers.

Tariffs and Trade Wars

Over the years, tensions have arisen between the US and China regarding trade practices. Tariffs have been imposed on each other’s goods, leading to trade wars that have disrupted markets and raised costs for businesses and consumers. The ebb and flow of these trade disputes have a direct impact on the US economy, affecting industries such as agriculture, technology, and manufacturing.

Supply Chain Dependency

A Chinese translator told me the US economy has become increasingly reliant on Chinese manufacturing and supply chains. This dependency has become especially evident in the wake of the COVID-19 pandemic, as disruptions in the supply chain highlighted vulnerabilities. Many US companies source components or finished goods from China, making them susceptible to disruptions caused by geopolitical tensions or natural disasters.

Intellectual Property and Technology Transfer

The issue of intellectual property theft and technology transfer has been a contentious one in US-China relations. Concerns have been raised about China’s practices, such as forced technology transfer, intellectual property theft, and unfair competition. These practices can stifle innovation and competitiveness in the US technology sector, which is a vital driver of the American economy.

Investment Flows

China’s influence extends to the realm of investment. Chinese investors have poured billions of dollars into the US, investing in businesses, real estate, and financial assets. This has the potential to boost the US economy by providing capital and creating jobs. However, it also raises concerns about national security and the influence of foreign entities on US businesses.

Currency Manipulation

China has been accused of manipulating its currency, the yuan, to gain an advantage in international trade. This practice can affect the competitiveness of US exports and has led to disputes between the two nations. Currency manipulation can also impact the global financial markets, causing uncertainty and volatility.

Energy and Natural Resources

China’s voracious appetite for energy and natural resources has global repercussions, including effects on the US economy. China’s demand for commodities like oil, coal, and metals can influence global prices and markets. This can impact US energy producers and resource exporters, creating opportunities and challenges for the US economy.

Geopolitical Considerations

The US-China relationship is not limited to economics; it also has significant geopolitical dimensions. Tensions in the South China Sea, cybersecurity concerns, and human rights issues can spill over into economic relations. These geopolitical factors can have a direct impact on trade and investment between the two nations.

Conclusion

China’s influence on the US economy is undeniable and multifaceted. As the world’s second-largest economy and a major trading partner, China’s policies and practices have far-reaching implications for the United States. The trade deficit, supply chain dependency, intellectual property issues, investment flows, currency manipulation, energy demand, and geopolitical tensions all play a role in shaping the economic relationship between these two nations.

It is essential for the United States to navigate this relationship carefully, balancing economic interests with national security and strategic considerations. Engaging in constructive dialogue and negotiation is key to addressing the challenges and opportunities presented by China’s role in the global economy.

As we move forward in this dynamic landscape, understanding the complexities of the US-China economic relationship will be vital for policymakers, businesses, and individuals alike. The interplay between these economic giants will continue to shape the trajectory of the global economy in the years to come.

The Best Banks in Tennessee: A Comprehensive Guide

Tennessee Banks


When it comes to managing our finances, choosing the right bank is crucial. Tennessee, known for its rich musical heritage, beautiful landscapes, and vibrant cities, is home to several reputable financial institutions. In this comprehensive guide, we will explore the best banks in Tennessee, taking into account their services, customer satisfaction, accessibility, and overall reputation. Whether you’re a resident of Nashville, Memphis, Knoxville, or any other city in the state, this article will help you make an informed decision when it comes to selecting a bank that suits your needs.

First Horizon Bank

Founded in 1864, First Tennessee Bank now First Horizon Bank has been a trusted financial institution for over a century. With a wide range of services and a strong presence throughout the state, First Tennessee Bank offers personal and business banking, mortgages, loans, and wealth management. They pride themselves on their exceptional customer service and innovative digital banking platforms, making banking convenient for their customers. Their extensive network of branches and ATMs ensures accessibility for individuals and businesses alike.

Pinnacle Financial Partners

Pinnacle Financial Partners has established itself as one of the leading banks in Tennessee. With a focus on personalized service and community involvement, Pinnacle offers a range of banking services, including checking and savings accounts, mortgages, loans, and investment options. Their commitment to building strong relationships with customers has earned them a reputation for exceptional customer satisfaction. Pinnacle’s convenient online and mobile banking platforms provide users with easy access to their accounts, making banking hassle-free.

Regions Bank

Regions Bank is a prominent financial institution that operates throughout the Southeast, including Tennessee. With a long history dating back to 1856, Regions Bank offers a comprehensive suite of banking services tailored to meet the needs of individuals, businesses, and corporations. From personal checking and savings accounts to wealth management and commercial banking solutions, Regions Bank is known for its reliability and commitment to customer service. Their user-friendly online and mobile banking platforms make managing finances convenient and efficient.

SunTrust Bank

SunTrust Bank, recently merged with BB&T to form Truist Financial Corporation, is another noteworthy bank in Tennessee. With a strong presence in the state, SunTrust Bank offers a wide range of financial products and services, including personal banking, business banking, mortgages, and wealth management. Some arboricultural consultants who bank here told me SunTrust’s emphasis on innovation is evident through their user-friendly digital tools, such as online and mobile banking, which provide customers with convenient access to their accounts. The merger with BB&T has further expanded their reach, providing customers with enhanced banking capabilities and an extensive network of branches and ATMs.

Bank of Tennessee

Founded in 1974, Bank of Tennessee has steadily grown to become one of the most trusted local banks in the state. With a focus on personalized service and community involvement, Bank of Tennessee offers a range of banking services, including personal and business banking, loans, mortgages, and investment options. Their commitment to understanding the unique needs of their customers sets them apart, and their dedicated team of professionals ensures a personalized banking experience. Bank of Tennessee’s online and mobile banking platforms provide users with the flexibility to manage their finances anytime, anywhere.

Conclusion

Choosing the right bank in Tennessee is a decision that should not be taken lightly. The financial institutions mentioned in this comprehensive guide have proven their reliability, customer satisfaction, and commitment to excellence. Whether you prioritize convenience, personalized service, or a strong community presence, these banks offer a range of services to meet your financial needs. Remember to consider factors such as accessibility, digital banking capabilities, and customer reviews when making your decision. By choosing one of the best banks in Tennessee, you can rest assured that your financial future is in capable hands.

The Best Banks in Texas

banks in Texas


Texas is one of the largest states in the United States of America, with a population of over 29 million people. It is also home to many banks, both large and small, that serve the financial needs of individuals and businesses throughout the state. In this article, we will explore some of the best banks in Texas.

Frost Bank

Frost Bank is one of the largest and oldest banks in Texas. The bank was founded in San Antonio in 1868 and has grown to become one of the top banks in the state. Frost Bank offers a wide range of personal and business banking services, including checking and savings accounts, loans, mortgages, and wealth management services.

Frost Bank has a strong reputation for excellent customer service and has consistently ranked highly in customer satisfaction surveys. The bank also offers a mobile app that allows customers to access their accounts and perform banking transactions on the go.

Wells Fargo

Wells Fargo is a national bank that has a strong presence in Texas. The bank offers a wide range of banking services, including checking and savings accounts, credit cards, loans, and mortgages. Wells Fargo is known for its strong financial stability and has consistently ranked highly in financial strength ratings.

Wells Fargo has a large network of branches and ATMs throughout Texas, making it easy for customers to access their accounts and perform banking transactions. The bank also offers a mobile app that allows customers to manage their accounts and perform transactions from their mobile devices.

Capital One

Capital One is another national bank that has a strong presence in Texas. The bank offers a wide range of banking services, including checking and savings accounts, credit cards, loans, and mortgages. Capital One is known for its strong customer service and has consistently ranked highly in customer satisfaction surveys.

A Texas concrete business owner told me Capital One has a large network of branches and ATMs throughout Texas, making it easy for customers to access their accounts and perform banking transactions. The bank also offers a mobile app that allows customers to manage their accounts and perform transactions from their mobile devices.

BBVA

BBVA is a global bank that has a strong presence in Texas. The bank offers a wide range of banking services, including checking and savings accounts, credit cards, loans, and mortgages. BBVA is known for its strong customer service and has consistently ranked highly in customer satisfaction surveys.

BBVA has a large network of branches and ATMs throughout Texas, making it easy for customers to access their accounts and perform banking transactions. The bank also offers a mobile app that allows customers to manage their accounts and perform transactions from their mobile devices.

Comerica

Comerica is a regional bank that has a strong presence in Texas. The bank offers a wide range of banking services, including checking and savings accounts, credit cards, loans, and mortgages. Comerica is known for its strong customer service and has consistently ranked highly in customer satisfaction surveys.

Comerica has a large network of branches and ATMs throughout Texas, making it easy for customers to access their accounts and perform banking transactions. The bank also offers a mobile app that allows customers to manage their accounts and perform transactions from their mobile devices.

First National Bank Texas

First National Bank Texas is a regional bank that has a strong presence in Texas. The bank offers a wide range of banking services, including checking and savings accounts, credit cards, loans, and mortgages. First National Bank Texas is known for its strong customer service and has consistently ranked highly in customer satisfaction surveys.

First National Bank Texas has a large network of branches and ATMs throughout Texas, making it easy for customers to access their accounts and perform banking transactions. The bank also offers a mobile app that allows customers to manage their accounts and perform transactions from their mobile devices.


How to Obtain Financing to Buy a Jacksonville Home

financing Jacksonville Real estate


Obtaining financing to buy a home in Jacksonville or any other location typically involves similar steps. Here is a step-by-step guide to help you secure financing for your new home:

Review your credit report

Obtain your credit report from one of the three major credit bureaus (Equifax, Experian, or TransUnion). Check for any errors and take steps to correct them, if necessary. A higher credit score will help you secure better mortgage terms.

Reviewing your credit report is important for several reasons:

Check for errors: Your credit report contains information about your credit history, including your payment history, balances, and credit limits. It’s important to review your credit report regularly to make sure there are no errors or inaccuracies that could be negatively affecting your credit score.

Detect fraud: By reviewing your credit report regularly, you can detect any fraudulent activity on your accounts. This could include unauthorized credit inquiries, new accounts opened in your name, or charges you did not make.

Improve your credit score: By reviewing your credit report, you can identify areas where you can improve your credit score. For example, if you have high balances on your credit cards, you can work on paying them down to improve your credit utilization ratio.

Prepare for major financial decisions: If you plan on applying for a loan or credit card, or even renting an apartment or applying for a job, it’s important to review your credit report ahead of time. This way, you can address any issues or errors before they negatively impact your application or creditworthiness.

Determine your budget

Calculate how much you can afford to spend on a home by considering your monthly income, expenses, and any existing debts. A general rule of thumb is that your mortgage payment should not exceed 28-30% of your monthly gross income.

Here are some key factors to consider:

Calculate your income: Start by calculating your monthly income from all sources. This includes your salary, any bonuses, rental income, or any other source of income.

Determine your monthly expenses: Next, calculate all of your monthly expenses, including rent, utilities, car payments, credit card payments, and other bills.

Determine your debt-to-income ratio: Your debt-to-income ratio is the percentage of your monthly income that goes toward paying debts. Lenders typically use this ratio to determine your creditworthiness. Aim for a debt-to-income ratio of 36% or less.

Check your credit score: Your credit score will affect your ability to qualify for a mortgage and the interest rate you’ll pay. Check your credit score and report from one of the three major credit bureaus (Equifax, Experian, or TransUnion) and take steps to improve it if necessary.

Consider your down payment: The amount of money you have for a down payment will affect the size of your mortgage and your monthly payments. Typically, a down payment of 20% of the home’s purchase price is ideal, but you may be able to qualify for a mortgage with a smaller down payment.

Research the housing market: Look at homes in your desired Jacksonville neighborhoods and determine the price range for homes that meet your needs. Consider working with a real estate agent who can help you find homes within your budget.

Use an online mortgage calculator: Once you have a sense of your budget and down payment, use an online mortgage calculator to estimate your monthly payments, including principal, interest, taxes, and insurance.

Save for a down payment

Aim to save at least 20% of the home’s purchase price for a down payment to avoid paying private mortgage insurance (PMI). However, there are financing options available for lower down payments.

Here are some steps you can take to save for a down payment on a Jacksonville home:

Set a goal: Determine how much money you need to save for a down payment. Generally, a down payment is around 20% of the purchase price of the home. However, there are some mortgage programs that require lower down payments, such as FHA loans that require as little as 3.5% down. Once you know how much you need to save, set a realistic goal for yourself and establish a timeline for achieving it.

Create a budget: Review your income and expenses and create a budget that allows you to save money each month. Look for areas where you can cut back on expenses and redirect that money towards your down payment savings. Consider setting up automatic savings contributions to help you stick to your budget.

Explore down payment assistance programs: There are various down payment assistance programs available for first-time homebuyers, low-income families, and military personnel. Research these programs and see if you qualify for any of them.

Increase your income: Consider taking on a part-time job or side hustle to earn extra income. Use the extra money you earn to boost your down payment savings.

Reduce debt: High levels of debt can make it difficult to save for a down payment. Work on paying off high-interest debts first, such as credit card balances, to free up more money for savings.

Be patient and persistent: Saving for a down payment can take time and discipline. Stay focused on your goal, avoid temptation to spend money on unnecessary items, and stay committed to your budget and savings plan.

Research loan options

Familiarize yourself with the various types of mortgage loans available, such as conventional loans, FHA loans, VA loans, and USDA loans. Each loan type has its own requirements and benefits, so choose one that best fits your financial situation and goals.

Here are some steps to help you research loan options to buy a Jacksonville home:

Determine your budget: Before researching loan options, you need to determine how much you can afford to borrow. You can use online calculators to estimate your monthly mortgage payments and determine your maximum loan amount.

Research different loan types: There are several types of loans available to buy a home, including conventional loans, FHA loans, VA loans, and USDA loans. Each type of loan has its own requirements and eligibility criteria, so it’s important to research and understand them before making a decision.

Compare interest rates: Interest rates can vary significantly between lenders, so it’s important to shop around and compare rates. You can use online comparison tools to get an idea of the current rates, but it’s also a good idea to contact lenders directly to get a personalized quote.

Look for lender reviews: It’s important to choose a reputable lender, so be sure to read reviews from other borrowers before making a decision. You can find reviews on websites like Zillow, Google, and Yelp.

Get pre-approved: Once you’ve narrowed down your options, it’s a good idea to get pre-approved for a loan. This will give you an idea of how much you can borrow and make you a more attractive buyer to sellers.

Seek professional advice: Finally, it’s always a good idea to seek professional advice from a financial advisor or mortgage broker. They can help you navigate the loan process and ensure that you’re making an informed decision.

Get pre-approved

Contact several mortgage lenders to obtain pre-approval for a mortgage. This will give you an idea of how much you can borrow and demonstrate to sellers that you are a serious buyer. Be prepared to provide documentation such as pay stubs, tax returns, and bank statements.

Here are the steps you can follow to get pre-approved to buy a home in Jacksonville:

Check your credit score: Your credit score is one of the key factors that lenders use to determine whether you are eligible for a home loan. You can check your credit score for free through various online platforms. Aim for a credit score of at least 620 to increase your chances of being approved for a home loan.

Find a lender: Look for lenders who offer pre-approval for home loans in Jacksonville. You can start by asking your friends, family, or real estate agent for recommendations. You can also search online for lenders in Jacksonville.

Gather your financial documents: To apply for pre-approval, you will need to provide financial documents such as tax returns, pay stubs, bank statements, and proof of employment. Make sure you have all these documents ready.

Submit your application: Once you have found a lender and gathered your financial documents, you can submit your application for pre-approval. You may be able to submit your application online or in person.

Wait for the lender to review your application: The lender will review your financial documents and credit score to determine whether you are eligible for a home loan. They may also ask for additional information or documentation.

Receive your pre-approval letter: If you are approved for a home loan, the lender will provide you with a pre-approval letter. This letter will state the amount you are pre-approved to borrow, which can help you determine your home buying budget.

Find a real estate agent

Work with a local real estate agent familiar with the Jacksonville market. They can help you find a home within your budget and guide you through the home buying process.

If you’re looking for a real estate agent in Jacksonville, here are some steps you can take:

A tip I got from a sell my house fast Jacksonville realtor is ask for referrals from friends, family, or colleagues who have recently bought or sold a property in Jacksonville. They may be able to recommend an agent who they had a positive experience with.

Use online directories or websites that list real estate agents in Jacksonville, such as Zillow, Realtor.com, or Redfin. These sites can provide you with the agent’s contact information, customer reviews, and areas of expertise.

Check with the National Association of Realtors or the Florida Association of Realtors to find a licensed real estate agent in Jacksonville. You can search for agents by name or location on their websites.

Attend open houses in the area and meet agents in person. This can be a great way to get a sense of an agent’s personality and communication style before deciding to work with them.

Interview several agents before making a final decision. Ask them about their experience, track record, marketing strategy, and commission rates. Choose an agent who you feel comfortable with and who has a good understanding of the Jacksonville real estate market.

Make an offer

Once you’ve found a home you want to purchase, work with your real estate agent to submit a competitive offer based on comparable homes in the area.

Making an offer on a Jacksonville property typically involves the following steps:

Determine the value of the property: Research the market to determine the value of the property you are interested in. You can also hire a professional real estate agent to help you determine the property’s value.

Determine the amount of your offer: Once you know the value of the property, you can decide how much you want to offer. You may choose to offer the asking price or negotiate a lower price based on factors such as the condition of the property, the length of time it has been on the market, and the seller’s motivation to sell.

Draft a purchase agreement: A purchase agreement is a legal document that outlines the terms and conditions of the sale, including the purchase price, financing details, and any contingencies or conditions that must be met before the sale can be completed.

Submit your offer: Submit your offer to the seller or their representative, typically through your real estate agent.

Negotiate and finalize the offer: The seller may accept your offer, reject it, or make a counteroffer. If a counteroffer is made, you may need to negotiate the terms until both parties agree on the purchase price and conditions.

Sign the purchase agreement: Once the terms of the offer are agreed upon, both parties will sign the purchase agreement to finalize the sale.

Complete a home inspection

Hire a professional home inspector to assess the property for any issues or needed repairs. Depending on the results, you may need to renegotiate the purchase price or request repairs before closing.

Here are the general steps you can follow to complete a home inspection:

Gather the necessary tools and equipment: Before beginning the inspection, make sure you have all the necessary tools and equipment, such as a flashlight, ladder, moisture meter, electrical tester, and other specialized tools you may need depending on the type of inspection.

Inspect the exterior of the home: Begin by inspecting the exterior of the home, including the roof, gutters, siding, foundation, windows, doors, and landscaping. Look for any signs of damage, wear and tear, or other issues that may need to be addressed.

Inspect the interior of the home: Once you have completed the exterior inspection, move inside the home and inspect the interior. Check the walls, floors, ceilings, doors, windows, and other structural components. Look for any signs of water damage, leaks, cracks, or other issues.

Inspect the plumbing system: Check all the plumbing fixtures, including sinks, toilets, tubs, showers, and appliances that use water. Test the water pressure and look for any leaks or signs of water damage.

Inspect the electrical system: Check the electrical panel, outlets, and switches, and test them to ensure they are working properly. Look for any signs of outdated or faulty wiring, and check for any safety hazards.

Inspect the heating and cooling system: Test the heating and cooling systems, including the furnace, air conditioner, and ventilation system. Look for any signs of wear and tear, and ensure that they are working properly.

Test appliances and other systems: Check any other appliances or systems, such as the hot water heater, smoke detectors, and carbon monoxide detectors.

Document any issues: As you complete the inspection, make note of any issues or potential problems you identify. Take photos or videos as needed to document any issues.

Provide a report: Once you have completed the inspection, provide a detailed report to the homeowner or buyer. The report should include any issues you identified, along with recommendations for repairs or other actions that may be necessary.

Finalize your mortgage

After your offer is accepted and the home inspection is complete, work with your lender to finalize the mortgage. They will require an appraisal to determine the property’s value and ensure it meets their lending requirements.

Here are the steps to finalize your Jacksonville mortgage:

Review and sign your mortgage loan documents: Once you receive your mortgage loan documents, review them carefully and make sure that all the terms and conditions of the loan are accurate and what you agreed to. Sign the documents and return them to the lender.

Complete the closing process: The closing process involves several important steps, including a final review of the loan documents, payment of closing costs, and the transfer of ownership of the property. Make sure that you have all the necessary documentation and funds to complete the closing process.

Obtain homeowner’s insurance: Before the lender can finalize your mortgage, you will need to obtain homeowner’s insurance to protect your property against damage or loss. You will need to provide proof of insurance to the lender.

Prepare for the first mortgage payment: You will need to make your first mortgage payment on the date specified in your loan documents. Make sure that you have the necessary funds available to make the payment on time.

Communicate with your lender: Stay in contact with your lender throughout the finalization process and ask any questions you may have. Be sure to respond promptly to any requests for additional information or documentation.

Close on the home

Attend the closing meeting, where you’ll sign all necessary paperwork, pay your down payment and closing costs, and finalize the transaction. Once complete, you’ll receive the keys to your new Jacksonville home.

Here are the general steps you may need to take:

Hire a Real Estate Agent: A good real estate agent can help you find the right home, negotiate with the seller, and guide you through the closing process.

Obtain a Preapproval for a Mortgage: Getting pre-approved for a mortgage will help you understand what type of home you can afford and give you more bargaining power during the negotiation process.

Make an Offer: Once you’ve found a home you like, you’ll need to make an offer to the seller. Your real estate agent can help you write up the offer and negotiate with the seller on your behalf.

Get a Home Inspection: It’s important to have a professional inspection of the home to identify any issues that may need to be addressed before closing.

Obtain Title Insurance: Title insurance protects you and the lender from any legal claims that may arise against the property.

Complete the Closing Documents: You’ll need to sign various documents, including the purchase agreement, mortgage paperwork, and other legal forms.

Pay Closing Costs: There will be closing costs associated with the purchase of your home, which may include appraisal fees, title fees, and other expenses.

Final Walk-Through: Before closing, you’ll have an opportunity to walk through the home and ensure that any repairs or other issues have been addressed.

Close on the Home: The final step is to sign all the necessary paperwork and pay the remaining balance of the purchase price. Once the transaction is complete, you’ll receive the keys to your new home.

Remember, each home buying situation is unique, so it’s essential to work closely with professionals, such as mortgage lenders and real estate agents, to guide you through the process.