Killing Haitians Book Review: Why It Stands Out Among True Survival Stories in Haiti—and How Bank Financing Can Expand Its Reach

Banking News for True survival stories in Haiti

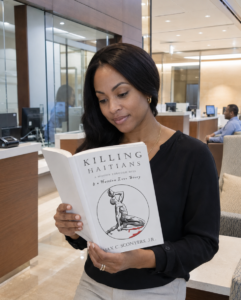
Some books are built around an idea. Others are built around an experience that refuses to stay buried. Killing Haitians: A Mission Through Hell & A Haitian Love Story belongs to the second group. Written by Max C. Sconyers Jr., the book follows a thirty-day journey through Haiti that reportedly included being held at gunpoint, kidnapped, injured, rescued, and exposed to deadly violence. The result is a memoir shaped by danger, vulnerability, human connection, and the difficult emotional weight that follows a person home.

That combination gives the book a place among True survival stories in Haiti while also separating it from ordinary travel writing. The appeal is not limited to dramatic incidents. The narrative reaches into the author’s state of mind, his relationships, the people he encountered, and the contrast between brutality and compassion. It presents Haiti as a complicated human setting rather than a convenient background for adventure.

A book with this kind of emotional and cultural reach still needs a practical path to readers. Publishing does not end when a manuscript becomes available for sale. Visibility requires distribution, advertising, public relations, review outreach, video production, events, digital campaigns, and sustained audience development. Carefully planned bank financing can help fund that work, provided the borrowing decision is tied to a realistic marketing plan, measurable goals, and a responsible repayment strategy.

A Survival Memoir With More Than Physical Danger

The most memorable part of Killing Haitians is the collision between external danger and internal struggle. According to the book’s official description, Sconyers entered Haiti with good intentions but was already dealing with turmoil in his own mind. That detail matters because it prevents the story from becoming a simple account of a fearless traveler overcoming a series of obstacles. The author appears in the narrative as a vulnerable participant whose judgment, emotions, and limitations affect how the journey unfolds.

During the thirty days covered by the book, the author says he received two bloody noses, faced a gun, endured kidnapping, and was eventually rescued. He also describes witnessing two Haitians being beaten and killed. Those events provide the urgency expected from a survival memoir, but the book’s stronger value comes from the consequences surrounding them. Violence changes the people who see it. Rescue creates gratitude, dependence, and sometimes guilt. Returning home does not automatically resolve fear, grief, anger, or the memory of decisions made under pressure.

The subtitle, A Mission Through Hell & A Haitian Love Story, signals the book’s wider emotional range. The account includes danger and death, but it also includes affection, unexpected help, spiritual reflection, and human relationships. That tension gives the story weight. Haiti is not reduced to a symbol of violence. It is shown as a place where suffering, courage, beauty, poverty, friendship, and contradiction can exist at the same time.

Why the Book Stands Apart From Conventional Travel Memoirs

Many travel books are structured around destinations, meals, landmarks, and personal discovery. Killing Haitians uses travel as the doorway into a much harsher experience. The reader is not being guided through an itinerary. The reader is following a man whose control over his surroundings collapses and whose survival begins to depend on the choices of other people.

That difference creates immediacy. Being held at gunpoint is not presented as a colorful travel mishap. Kidnapping is not treated as an entertaining detour. Rescue is not simply a dramatic ending. Each event changes the emotional direction of the narrative and deepens the book’s central themes of vulnerability and dependence. The story recognizes that survival often involves strangers, local relationships, and moments of compassion that are rarely visible in a headline.

The first-person perspective also gives the book a form of authority that general reporting cannot reproduce. News reports can document instability, crime, political conflict, and humanitarian hardship. A firsthand memoir can show how confusion develops minute by minute, how fear affects judgment, and how quickly an ordinary plan can become dangerous. That personal scale allows readers to understand the emotional texture of an event rather than only its public significance.

The Ethical Importance of Marketing the Story Carefully

A title as forceful as Killing Haitians naturally attracts attention, but the long-term reputation of the book will depend on how its message is presented. Effective promotion should make clear that the book is a firsthand survival account and a personal reckoning, not a broad judgment against Haitian people. Its own description emphasizes the humanity, courage, suffering, and relationships the author encountered. Marketing should preserve that balance.

The strongest campaign would focus on the author’s lived experience, the thirty-day timeline, the kidnapping and rescue, the witnessing of violence, and the emotional and spiritual aftermath. It should also emphasize the Haitian individuals whose actions, stories, and humanity shaped the journey. This approach gives readers a truthful reason to pay attention without turning an entire nation into a marketing device.

That distinction is important for reviewers, librarians, churches, book clubs, travel audiences, and readers interested in memoir. Responsible positioning can open more doors than shock-based promotion alone. A carefully framed campaign can place the book within discussions about survival literature, Christian social issues, international travel, trauma, Haiti, humanitarian work, and the moral complexity of witnessing violence.

Why Serious Book Marketing Requires Working Capital

Independent books often face a visibility problem rather than a quality problem. A compelling story can remain unknown because the author lacks the capital to produce a professional campaign. Marketing expenses arrive before sales results are guaranteed. A trailer must be produced before it can attract viewers. Advertisements must run before they can generate orders. Publicists, designers, editors, event organizers, and distribution partners may require payment before the campaign creates revenue.

Bank financing can help bridge that gap. In basic terms, a loan provides funds that are repaid under agreed terms, usually with interest. For a book campaign, borrowed capital might support a defined launch or growth plan rather than forcing every marketing activity to wait for current book revenue.

The financial logic must remain disciplined. Borrowing makes sense only when the author or publishing business understands the payment schedule, total borrowing cost, campaign budget, expected conversion path, and downside risk. Financing should create an organized opportunity for growth, not disguise the absence of a marketing strategy.

The amount borrowed should also match the stage of the publishing business. A first marketing test may require only enough capital to improve the website, create several videos, run a controlled advertising campaign, and contact relevant media outlets. A larger request may be appropriate only after smaller campaigns have produced dependable information about audience interest, conversion rates, and sales.

The Current Bank Lending Environment Rewards Preparation

Recent bank financing news reinforces the need for a strong application. The Federal Reserve’s April 2026 Senior Loan Officer Opinion Survey reported that modest net shares of banks tightened standards for commercial and industrial loans to firms of all sizes. Banks also reported higher premiums on riskier loans, tighter covenants, and stricter collateral requirements in parts of the market.

For an author, publisher, or small media company, that environment makes preparation especially important. A lender will be more interested in a documented business plan than in general confidence that a book deserves a larger audience. The application should explain how money will be spent, how sales will be tracked, which assets already exist, what revenue sources support repayment, and what happens if the campaign performs below expectations.

The FDIC’s Small Business Lending Survey also underscores the continuing importance of banks in small-business credit. The survey examines how banks underwrite, approve, and manage small-business loans. Its existence reflects a practical reality for authors and publishers. Smaller enterprises often need financing structures that differ from those used by large corporations.

A book venture should approach lenders with clear records, realistic projections, and a request sized to the actual campaign. Useful documentation may include current sales statements, retailer reports, website traffic, advertising history, publishing agreements, business tax returns, existing debt, available collateral, and a month-by-month campaign budget.

Financing Options That May Fit a Book Marketing Campaign

A traditional term loan can provide a fixed amount for a defined campaign, such as a national publicity push, an audiobook launch, or a coordinated advertising season. The business receives a lump sum and makes scheduled payments according to the loan agreement. This structure can work well when the total project cost is already known.

A business line of credit may be better suited to recurring expenses because funds can be drawn as needed, subject to the lender’s terms. An author might use the line for monthly advertising, promotional travel, event fees, printing costs, contractor payments, or public relations expenses. Interest is generally connected to the amount drawn rather than the entire approved limit, although terms vary by institution.

A business credit card can cover smaller purchases, but high interest costs can make it a poor choice for balances that remain unpaid. Credit cards are most useful when purchases can be repaid quickly and the account is not being used to cover an open-ended campaign with no dependable source of repayment.

Government-backed programs may also be relevant for eligible businesses. The U.S. Small Business Administration’s 7(a) loan program allows approved financing for purposes that include short- and long-term working capital. Eligibility, permitted uses, creditworthiness, and repayment ability remain subject to program and lender requirements. The program is not a guarantee that a particular author or publishing company will qualify, but it gives established small businesses another avenue to explore.

Banking regulators continue to publish information about credit availability. The Office of the Comptroller of the Currency’s release on 2024 small-business lending data reflects the broader public interest in how credit reaches small businesses and communities. For a publishing venture, the practical lesson is to compare lenders rather than assume every bank evaluates a creative business in the same way.

Building a Marketing Plan Worth Financing

A lender-ready marketing plan should connect every expense to a clear business purpose. A professional book trailer can introduce the emotional force of the story. Search advertising can reach readers looking for survival memoirs, Haiti books, Christian nonfiction, and real-life travel accounts. Social media video can give the author a direct voice. Podcast appearances can place the book in front of audiences interested in faith, danger, trauma, international affairs, and personal transformation.

The plan can also include outreach to book reviewers, libraries, independent bookstores, church groups, travel organizations, universities, Haitian cultural organizations, and memoir-focused reading communities. Paid promotion becomes more effective when it supports genuine editorial interest, reader discussion, and credible third-party coverage.

A strong campaign should identify the role of each channel. Search advertising can capture existing interest. Social media can introduce the story to people who have never heard of the book. Email marketing can maintain contact with readers over time. Public relations can generate interviews and editorial mentions. Book review outreach can create third-party validation. Events and speaking appearances can transform the author from a name on a cover into a person audiences remember.

Every channel should have a budget, timeline, audience, and measurement method. Website traffic, email subscriptions, trailer views, retailer clicks, cost per sale, event attendance, review growth, and repeat engagement can all provide useful signals. The campaign should not depend on a single viral moment. It should build several paths through which a reader can discover the book, understand its subject, trust its presentation, and decide to purchase it.

Using Borrowed Money Without Losing Control of the Story

Debt can expand reach, but it can also create pressure that leads to poor marketing decisions. An author who borrows too much may chase sensational publicity, overspend on broad advertising, or continue an ineffective campaign simply because money has already been committed. A smaller, staged financing plan can protect both the business and the integrity of the book.

The first stage might fund a trailer, improved sales pages, professional creative assets, and a limited advertising test. Results from that stage can guide the next investment. Strong conversion data may support a broader campaign. Weak results may reveal that the message, audience, pricing, or purchase process needs improvement before more money is spent.

The campaign budget should separate essential expenses from optional ones. Essential expenses might include the website, sales tracking, professional creative work, email infrastructure, and targeted outreach. Optional expenses might include expensive travel, large print runs without confirmed demand, broad advertising with weak audience targeting, or premium services that do not have a measurable connection to book sales.

Transparency in lending is also receiving continued regulatory attention. The Consumer Financial Protection Bureau’s small-business lending resources track federal requirements affecting how covered lenders collect and report information about small-business credit applications. Authors considering financing should still review all terms personally, compare offers, and seek qualified financial or legal guidance when the obligation is significant.

How Authority and Credibility Can Expand the Campaign

The value of a book marketing campaign is not measured only by the number of advertisements purchased. Credibility grows when respected websites, reviewers, journalists, organizations, and subject-matter experts discuss the book in a meaningful context. Those mentions can produce referral traffic, citations, interviews, backlinks, retailer searches, and long-term discovery.

For Killing Haitians, credible coverage should focus on the substance of the story. Articles can examine the role of firsthand testimony in survival literature. Interviews can explore how the author processed danger after returning home. Faith-based publications can discuss the spiritual consequences of witnessing violence. Travel publications can address the difference between ordinary tourism and entering an unfamiliar environment without adequate preparation.

Universities, libraries, cultural organizations, and book clubs may also provide opportunities for serious discussion. Outreach should be personalized rather than distributed as an identical mass email. Each recipient should receive a clear explanation of why the book relates to that publication, organization, course, audience, or event.

This approach can also strengthen the book’s online authority. Search engines are more likely to recognize a title when independent websites mention it in relevant, well-written content. Readers are more likely to trust the book when they encounter thoughtful reviews and interviews rather than seeing only advertisements created by the author.

Bank financing can support this work by funding professional outreach, media materials, public relations assistance, review copies, speaking events, travel, and supporting content. The goal should be to create useful reasons for reputable organizations to discuss the book, not simply to purchase links or manufacture attention.

A Wider Audience for a Difficult and Human Story

Killing Haitians has the ingredients of a book that can reach several audiences at once. It offers the urgency of a survival account, the uncertainty of dangerous travel, the emotional depth of memoir, and the spiritual tension of a man trying to understand what happened to him. Its strongest marketing advantage is not danger by itself. It is the relationship between danger, personal responsibility, rescue, love, trauma, and the humanity of the people encountered along the way.

A larger campaign could introduce the book to readers who would never find it through a retailer search alone. Earned media, interviews, reviews, video storytelling, community conversations, and carefully targeted advertising can work together. Bank financing can provide the working capital needed to coordinate those efforts rather than launching them one at a time without enough support.

The purpose of financing should remain clear throughout the process. Money does not create meaning, and advertising cannot replace a story worth reading. Financing can give a meaningful story the professional structure, repetition, and distribution needed to reach the people most likely to value it.

Conclusion

Killing Haitians: A Mission Through Hell & A Haitian Love Story stands out because it combines physical danger with emotional exposure. Max C. Sconyers Jr.’s account is presented as more than a record of guns, kidnapping, injury, rescue, and witnessed violence. It is a story about the people involved, the choices made under pressure, the internal struggle carried into Haiti, and the memories carried back home.

That depth gives the book a foundation for lasting interest, but lasting interest still requires visibility. A responsible financing strategy can support the trailer, publicity, digital advertising, outreach, events, and distribution work needed to place the book before a broader audience. The best approach is measured, documented, and tied to clear results. Borrowed capital should strengthen the campaign without distorting the story or placing the business under an obligation it cannot reasonably manage.

With respectful positioning, disciplined planning, and carefully chosen financing, Killing Haitians can move beyond a single publication launch and become part of a wider conversation about survival, faith, Haiti, trauma, human connection, and the cost of returning home after an experience that changed everything.
Banking on Backyard Luxury: How to get Financing for the Best Pool Contractors Near Me in California’s Peninsula Area

Banking News for Pool Contractors Near Me Peninsula Area

A custom swimming pool can turn a California Peninsula backyard into a private retreat, an entertainment space, and a natural extension of the home. In communities where outdoor living is possible through much of the year, a thoughtfully designed pool can become the center of family gatherings, quiet evenings, weekend celebrations, and everyday relaxation. The finished space may include landscaping, lighting, patios, shade structures, fire features, spas, outdoor kitchens, and other elements that make the yard feel complete. 🏡💧

That kind of transformation requires more than choosing an attractive pool design. It requires a realistic financial plan that accounts for design work, construction, site preparation, permits, materials, equipment, landscaping, and unexpected conditions discovered after work begins. Financing should be considered at the start of the planning process rather than after a contractor has already prepared an ambitious proposal.

California’s size, wealth, housing market, and high cost of living create a financial environment unlike that of many other states. The broader economy of California includes major financial, technology, real estate, professional-services, and construction sectors, with significant economic activity concentrated in coastal communities and the San Francisco Bay Area. Those conditions can influence property values, borrowing decisions, contractor pricing, and the availability of home-improvement financing.

A successful pool project begins when the homeowner’s design goals, contractor selection, available equity, monthly budget, and financing structure all support one another.

Begin With the Complete Backyard Budget

The first number a homeowner receives may represent only the pool itself. A complete project budget can be considerably broader. Excavation, grading, drainage, engineering, access limitations, retaining walls, utility relocation, electrical work, decking, fencing, landscaping, outdoor lighting, pool equipment, and permit-related expenses may all affect the final amount.

Peninsula properties often have characteristics that require additional planning. A narrow side yard may limit equipment access. A sloped lot may require structural or drainage solutions. Existing landscaping may need to be removed and restored. Local requirements may influence fencing, setbacks, equipment placement, energy efficiency, and inspections. A proposal that appears affordable at first can become difficult to finance when essential site work is added later.

Homeowners should request a detailed written proposal that separates major project components. Allowances should be clearly identified, along with exclusions and optional features. The financing amount should include the work required to complete a safe, functional, and visually cohesive outdoor environment, rather than covering the pool shell while leaving the surrounding yard unfinished.

A contingency reserve also belongs in the financial plan. Construction occasionally reveals soil issues, underground utilities, drainage complications, or material changes that could not be fully confirmed before excavation. Keeping a separate reserve reduces the chance of placing unexpected expenses on high-interest credit cards near the end of the project.

Match the Financing Method to the Project

Several financing methods may be available, but they do not carry the same costs, risks, or repayment structures. The right choice depends on the homeowner’s equity, credit profile, income, existing mortgage, available cash, and expected length of time in the home.

Cash offers simplicity and avoids interest charges, although using too much cash can weaken a household’s emergency reserves. A balanced approach may involve paying for design work or a deposit with available funds while financing the larger construction balance.

A home equity loan generally provides a lump sum with a defined repayment schedule. This structure may suit a project with a firm price and predictable payment milestones. Because the loan is secured by the property, homeowners should carefully evaluate the monthly obligation and the consequences of missed payments.

A home equity line of credit provides access to funds over a draw period. That flexibility may work well when contractor payments are divided into stages or when the final cost depends on selections made during construction. Rates and payments can change depending on the lender and loan terms, so the agreement deserves a careful review.

A cash-out refinance replaces the existing mortgage with a larger mortgage and provides the difference in cash. This can be useful in certain circumstances, but it also changes the financing of the entire home. Closing costs, the new interest rate, the repayment period, and the amount already paid toward the existing mortgage should all be considered before proceeding.

An unsecured home-improvement or personal loan does not use the home as collateral. Approval may be faster, but borrowing costs can be higher than those associated with secured financing. This option may be more appropriate for a smaller project, a limited remaining balance, or a homeowner who prefers not to borrow against home equity.

Some contractors also work with third-party financing companies. Convenience should not replace comparison shopping. Contractor-arranged financing should be evaluated alongside offers from banks and credit unions, with attention given to the annual percentage rate, origination fees, promotional periods, prepayment terms, and total repayment amount.

Follow California Financial Conditions Before Borrowing

Pool financing decisions do not take place in isolation. Employment conditions, household income, inflation, lending standards, real estate activity, and consumer debt can all influence what feels affordable.

The California Department of Finance economic and revenue updates provide ongoing information about state economic trends and cash receipts. The department publishes its Finance Bulletin during most months of the year and provides current and past editions for comparison. Reviewing this type of information can help homeowners understand the wider financial climate before accepting a substantial new obligation.

State-level developments can also affect lending practices and consumer protections. The California Department of Financial Protection and Innovation news center publishes regulatory announcements, enforcement actions, consumer alerts, and financial-industry updates. This is a valuable source for homeowners who want to stay informed about financial companies operating within California.

California financial news should not be used to predict exactly where interest rates or home prices will move. It can still provide useful context. A household with uncertain income, rising revolving debt, or plans to move soon may need a more conservative financing strategy than a household with stable earnings, strong reserves, and a long-term commitment to the property.

Compare Banks, Credit Unions, and Financing Companies

The most convenient lender does not always offer the strongest overall terms. Homeowners should compare several offers using the same requested loan amount and repayment period. A low advertised rate may be offset by fees, variable-rate exposure, required account relationships, or a longer repayment schedule that increases the total interest paid.

The Federal Reserve Bank of San Francisco banking resource center provides research and information related to banking supervision, business lending, community banking, financial stability, and economic conditions throughout the Federal Reserve’s western district. The San Francisco Fed explains that banking supervision involves federal agencies as well as state banking authorities, each overseeing institutions organized under different charters.

Consumers can also use the FDIC State Banking Performance Summary to review financial and ratio information for FDIC-insured institutions by state. This does not replace a personal loan comparison, but it provides an additional public resource for understanding the banking environment and the institutions serving California communities.

A complete comparison should account for the interest rate, whether the rate is fixed or variable, lender fees, appraisal expenses, closing costs, minimum draws, early-termination provisions, repayment length, and the total amount expected to be repaid. Monthly affordability matters, but a low payment created by stretching the loan across many years can make a backyard project much more expensive.

Prepare a Strong Financing Application

Lenders typically want a clear picture of the borrower’s ability to repay. Homeowners can make the process smoother by gathering income documentation, recent account statements, mortgage information, property details, insurance records, debt information, and the contractor’s written proposal before submitting an application.

Credit balances should be reviewed before applying. Large purchases made shortly before the application may affect available credit, monthly obligations, or underwriting calculations. Opening several new accounts at once can also complicate the financial picture presented to a lender.

The contractor’s estimate should be detailed enough for the lender to understand what is being financed. A vague one-page quote may create delays, particularly when the loan is tied to home equity or construction draws. The proposal should identify the project address, major work categories, payment schedule, expected timeline, and responsibility for permits and inspections.

Homeowners searching for Pool Contractors Near Me Peninsula Area should bring the contractor into the financial-planning conversation early. An experienced pool and landscape company can help clarify which elements belong in the initial construction phase and which features can be added later without compromising the overall design.

Choose the Contractor Before Finalizing the Loan Amount

Financing approval should never become permission to spend the maximum amount available. The contractor, project scope, property conditions, and household budget should determine the appropriate borrowing amount.

A strong contractor should be able to explain the relationship between the pool and the surrounding landscape. Drainage, circulation paths, equipment placement, privacy, sunlight, existing architecture, and future maintenance all affect the long-term success of the project. A pool placed without considering the rest of the yard may require expensive corrections or additions later.

The written agreement should align with the lender’s disbursement process. Payment milestones should correspond to measurable progress, and the homeowner should understand which selections can change the price. Verbal upgrades made during construction can quickly strain a carefully arranged loan.

Price remains important, but the lowest proposal may exclude essential work or rely heavily on allowances. A more complete proposal can be easier to finance because it reduces uncertainty. Clear documentation also helps the homeowner compare competing bids on equal terms.

Keep the Pool Investment Proportional to the Property

A luxury pool should feel appropriate for the home, neighborhood, lot, and intended lifestyle. Borrowing for every available upgrade can create a project that looks impressive while placing unnecessary pressure on the household budget.

The most valuable features are often the ones that improve daily use. Reliable equipment, functional decking, thoughtful lighting, comfortable seating areas, safe access, strong drainage, and landscaping that provides privacy may contribute more to enjoyment than a long list of decorative upgrades.

Homeowners should also consider ongoing ownership costs. Water, electricity, heating, routine service, chemicals, repairs, landscaping, and insurance can continue long after the construction loan is repaid. Financing calculations should leave enough room in the monthly budget for maintenance as well as the loan payment.

California’s public finance environment offers useful perspective on the importance of matching long-term obligations with durable assets. The California State Treasurer’s financial news and releases cover state bond sales, access to capital, banking issues, financial programs, and other developments involving California’s financial future. While state financing operates on a much larger scale, the underlying discipline remains relevant to homeowners: borrowing works best when the repayment structure fits the useful life and purpose of the investment.

Protect Financial Flexibility During Construction

Once construction begins, it becomes easy to approve upgrades based on emotion. A different tile, larger patio, upgraded lighting package, or additional water feature may seem modest on its own. Several changes combined can create a meaningful increase in the final balance.

A written change-order process protects the budget. Every change should identify the price, effect on the schedule, and effect on other parts of the project. The homeowner should confirm that enough cash or available credit remains before authorizing additional work.

It is also wise to keep emergency savings separate from the project account. A pool should improve the home without leaving the household vulnerable to an unrelated medical expense, vehicle repair, temporary loss of income, or major home-system failure.

California’s Infrastructure and Economic Development Bank demonstrates how structured financing is used to support public infrastructure and private development across the state. IBank provides financing assistance, issues bonds, supports public agencies, and leverages state and federal resources for economic-development activity. Although its programs are not standard residential pool loans, its work illustrates the broader principle that well-planned financing connects money to a defined project, documented purpose, and realistic repayment source.

Conclusion

Financing a luxury pool in California’s Peninsula communities requires the same care that goes into designing the finished backyard. The strongest plan begins with a complete project estimate, a qualified contractor, a realistic household budget, and a financing method that fits both the property and the borrower.

Banks, credit unions, home-equity products, personal loans, and contractor-arranged programs can all play a role. The best option is the one that provides sufficient funding without placing unnecessary pressure on the homeowner’s long-term financial stability. Rates, fees, collateral, payment changes, repayment length, and total borrowing costs deserve as much attention as tile selections, decking materials, and water features.

A carefully financed pool becomes more than a construction project. It becomes a lasting outdoor environment designed for the way the household actually lives. With clear proposals, disciplined borrowing, credible financial information, and a contractor who understands the entire property, homeowners can move from an empty yard to a polished Peninsula retreat with greater confidence. 💰🌴

Banking on Clean Trailers: Why Smart Businesses Are Investing in Professional Trailer Wash Services

Banking News for Trailer Wash

In the business world, the word “banking” usually brings to mind capital, loans, investments, risk management, and long-term financial planning. But smart business owners know that protecting an investment is not limited to what happens inside a bank. It also includes how a company maintains the equipment, vehicles, trailers, and physical assets that keep daily operations moving. For companies that depend on trailers for hauling, delivery, storage, travel, or mobile service, professional trailer cleaning is more than a cosmetic choice. It is a business decision that can support brand image, asset protection, resale value, and operational confidence. 💼

A clean trailer says something before a business owner, driver, contractor, or sales representative ever speaks. It communicates that the company is organized, professional, and attentive to detail. A neglected trailer can send the opposite message, even if the business behind it is excellent. That is why more companies are treating exterior trailer care like part of their broader asset management strategy. Just as business owners follow financial updates from trusted sources like American Banker to stay informed about the money side of business, they should also pay attention to the physical assets that help generate that money.

Professional trailer washing has become especially important for businesses that rely on first impressions, equipment longevity, and customer trust. Whether a trailer is used by a contractor, landscaper, delivery company, mobile service provider, recreational brand, or fleet-based business, keeping it clean can help preserve value and improve how the company is perceived. Smart businesses are no longer seeing trailer cleaning as an occasional chore. They are banking on clean trailers as part of a bigger strategy to protect their investments.

The Financial Mindset Behind Clean Equipment

Banking is built around the idea of responsible management. Businesses borrow, save, invest, and plan because money must be protected and used wisely. That same mindset applies to physical assets. A trailer may not sit inside a financial account, but it still represents real money. It was purchased, financed, customized, branded, insured, maintained, and used to support revenue. When that trailer is ignored, the business risks allowing dirt, road grime, oxidation, salt, mold, mildew, and stains to slowly reduce the asset’s appearance and condition.

The Wikipedia page on banking explains how financial institutions support money movement, lending, deposits, and broader economic activity. For business owners, that larger financial world connects directly to everyday decisions. A company may finance a trailer through a loan, count it as a business asset, depreciate it for tax purposes, or use it to generate income. Because of that, keeping the trailer in better condition is not just about pride. It is about protecting something the company has already paid for and may continue paying for.

When owners think like investors, maintenance becomes easier to justify. A clean trailer can help reduce avoidable deterioration, support a stronger resale presentation, and keep branded equipment looking professional on the road. In industries where customers judge reliability based on what they can see, the condition of a trailer can influence trust before a service even begins.

Why Trailer Appearance Matters to Customer Trust

Customers often make quick judgments. They may not know how skilled a contractor is, how reliable a delivery company is, or how experienced a mobile service provider is when they first see a trailer pull into the driveway or parking lot. What they do see is the condition of the equipment. A trailer covered in streaks, grime, black marks, stains, or dull buildup can make a business look careless, even if the work itself is high quality.

That matters because trust is part of every business transaction. Banks work hard to maintain public confidence, and organizations like the Federal Deposit Insurance Corporation regularly publish updates connected to banking stability, consumer confidence, and financial developments. While trailer appearance may seem far removed from bank regulation, the principle is similar. People trust what appears stable, maintained, and professional.

A clean trailer can help reinforce that trust. For contractors, it can make jobsite arrivals look more polished. For mobile businesses, it can turn the trailer into a moving advertisement. For delivery companies, it can make the brand feel more dependable. For recreational and travel-related businesses, it can create a better customer experience. The trailer becomes part of the company’s public image, and professional washing helps keep that image working in the business’s favor.

Clean Trailers Help Protect Business Assets

Trailers face constant exposure. Road film, bugs, dirt, brake dust, rain, sun, salt, tree sap, bird droppings, algae, and environmental pollutants can all build up on exterior surfaces. Over time, that buildup can make a trailer look older than it really is. Depending on the trailer material and finish, grime can also contribute to staining, fading, corrosion concerns, and surface damage.

This is where professional trailer washing becomes an asset protection tool. A high-quality cleaning process can help remove contaminants before they become harder to manage. It can also make routine inspections easier because damage, cracks, wear, and seal issues are more visible on a clean surface. Business owners who want to protect their equipment should view cleaning as part of ongoing maintenance, not something reserved only for special events or resale photos.

For businesses that follow financial news and banking trends through sources like the Federal Reserve, the idea of protecting assets should feel familiar. Companies monitor interest rates, lending conditions, and economic signals because those factors affect business decisions. In the same way, owners should monitor the condition of the assets they already have. A trailer that stays cleaner and better maintained may serve the company longer and present better when it is time to upgrade, sell, or trade.

Professional Trailer Wash Services Save Time and Improve Results

Business owners are busy. Employees are busy. Drivers, contractors, and operators often have full schedules. While basic rinsing can help, it does not always remove stubborn streaks, oxidation, mildew, or road grime. Professional washing products and services are designed to make the process more effective, especially for trailers that have been exposed to months or years of outdoor conditions.

Using a dedicated Trailer Wash solution can help businesses get a cleaner, better-looking trailer without relying on guesswork. Instead of using random household cleaners or harsh chemicals that may not be suited for the surface, a proper trailer wash product is made for the job. That matters because the goal is not just to make the trailer wet. The goal is to clean it properly, improve appearance, and support long-term care.

Time is another major benefit. A business that spends hours trying to clean trailers with the wrong approach may lose productivity. Professional washing methods can make the process more efficient, allowing companies to keep equipment presentable without turning maintenance into a major disruption. For small businesses especially, saved time often becomes saved money.

A Clean Trailer Can Strengthen Branding

Many trailers are branded with logos, phone numbers, website URLs, service areas, and company colors. That means the trailer is not just a piece of equipment. It is a rolling billboard. When the trailer is clean, the branding is easier to read and more visually appealing. When it is dirty, faded, or streaked, the marketing value drops.

This is especially important for businesses that depend on local visibility. A contractor parked outside a jobsite, a mobile service trailer driving through town, or a delivery trailer sitting in a customer’s driveway may be seen by dozens or even hundreds of people. Every one of those views can either support the brand or weaken it. A clean trailer helps make sure the impression is positive.

Banking news sources like the American Bankers Association often focus on trust, business trends, financial education, and industry confidence. Those same values apply to how a business presents itself in public. The cleaner and more consistent the brand appears, the easier it is for potential customers to feel confident reaching out.

Trailer Maintenance Supports Resale and Trade-In Value

Many businesses eventually upgrade equipment. A trailer may be sold, traded, replaced, or repurposed. When that time comes, condition matters. Buyers and dealers often notice appearance immediately. A clean, well-maintained trailer can look more appealing in photos, attract more interest, and create a stronger first impression during inspection.

While cleaning alone cannot fix mechanical problems or structural wear, it can help present the trailer in the best possible condition. It may also suggest that the owner cared for the equipment regularly. That perception can matter during negotiation. Just as a clean vehicle can be more attractive to a buyer, a clean trailer can help support the asset’s marketability.

Business owners who pay attention to financial planning understand that resale value is part of total cost of ownership. The more value a company can preserve, the better positioned it may be when making its next equipment decision. Updates from agencies such as the Office of the Comptroller of the Currency remind business owners that financial systems are built around accountability, oversight, and risk awareness. Equipment ownership benefits from the same kind of thinking.

Clean Equipment Can Boost Employee Pride

Customers are not the only people who notice equipment condition. Employees notice too. Drivers, crews, contractors, and team members often feel better representing a company when the equipment looks professional. A clean trailer can create a sense of pride and accountability. It tells the team that the business cares about standards.

This can be especially helpful for companies trying to build a stronger culture. Clean equipment sets expectations. It shows that details matter. It can also encourage workers to take better care of tools, vehicles, job materials, and customer spaces. When leadership invests in maintenance, employees are more likely to understand that professionalism is not optional.

In banking, confidence is everything. In field service, construction, hauling, travel, delivery, and mobile operations, confidence is also built through presentation. A clean trailer may seem simple, but it can contribute to a more professional company environment.

The Connection Between Banking, Business Planning, and Trailer Care

At first, banking and trailer washing may not seem connected. But for smart businesses, they meet at the same point: protecting value. Banking helps companies manage money. Trailer care helps companies maintain the assets that support that money. Both require planning, consistency, and a willingness to think beyond the immediate moment.

A business that invests in professional trailer washing is making a practical choice. It is choosing to protect equipment, improve presentation, support branding, and reduce neglect. That kind of decision fits into the same responsible mindset that guides budgeting, financing, insurance, marketing, and growth planning.

Business owners who stay informed through resources such as the Consumer Financial Protection Bureau newsroom understand that financial health often depends on clear decisions and informed action. Maintaining a trailer may not make headlines like banking policy, but it can still affect the everyday health of a business. Clean equipment supports the customer experience, the company image, and the long-term value of the assets used to serve clients.

Why Smart Businesses Are Making Trailer Wash Part of the Routine

The smartest maintenance habits are usually the ones that become routine. Waiting until a trailer looks terrible can make cleaning harder and less effective. Regular washing helps prevent buildup from becoming overwhelming. It also helps keep the trailer ready for customer visits, jobsite arrivals, marketing photos, inspections, and daily use.

A scheduled approach can work well. Some businesses may wash trailers weekly, monthly, seasonally, or after heavy use, depending on the industry. Trailers exposed to salt, mud, long-distance travel, or outdoor storage may need more frequent attention. The key is consistency. Just as companies do not wait until financial records are a mess to think about bookkeeping, they should not wait until equipment looks neglected to think about cleaning.

Professional trailer wash services and products make that routine easier to follow. They give business owners a specific solution instead of leaving them to improvise. That can lead to better results, less frustration, and a trailer that continues to represent the business well.

Conclusion

Banking on clean trailers is really about banking on smarter business habits. A trailer is more than something that follows behind a truck. For many companies, it is an investment, a mobile workspace, a storage solution, a delivery tool, and a public-facing part of the brand. When it looks clean and well cared for, it can support customer trust, employee pride, equipment value, and overall professionalism.

Smart businesses understand that success is built through many small decisions. Financial planning matters. Marketing matters. Customer service matters. Equipment maintenance matters too. Professional trailer washing gives companies a simple but powerful way to protect one of the assets that helps them operate, advertise, and grow.

A clean trailer may not appear on a balance sheet the same way a bank account does, but it still represents value. Companies that care for their trailers are showing customers, employees, and future buyers that they take their business seriously. In a competitive marketplace, that kind of attention can make a lasting difference. 🚛

Why Central Florida Banks Can’t Afford the Wrong General Contractor: The Hidden Risks Behind Every Renovation

Banking News for General Contractor Near Me in Central Florida

Banks are not ordinary commercial buildings. They contain sensitive customer information, advanced security systems, restricted work areas, expensive technology, cash-handling equipment, and spaces designed to protect employees and customers. Renovating a financial institution requires far more than installing new flooring, painting walls, or rearranging offices. Every construction decision can affect security, regulatory compliance, customer confidence, and the bank’s ability to continue operating.

This is especially important in Central Florida, where banks serve a rapidly changing population of homeowners, business owners, hospitality companies, construction firms, healthcare organizations, and technology enterprises. As communities grow, financial institutions must modernize branches, improve accessibility, strengthen security, and create more efficient customer experiences.

The wrong contractor can turn a carefully planned renovation into a costly operational problem. Delays, security oversights, code violations, technology disruptions, and poor workmanship can damage more than the building. They can damage the institution’s reputation.

Choosing an experienced commercial general contractor helps a Central Florida bank protect its property, employees, customers, and long-term investment. 🏦

Bank Renovations Require Specialized Construction Knowledge 🔐

A bank renovation is different from remodeling a traditional office, restaurant, or retail store. Financial institutions have unique operational requirements that must be considered before demolition or construction begins.

Contractors may need to work around vaults, teller lines, surveillance systems, alarm equipment, secure doors, data rooms, drive-through banking lanes, safe-deposit areas, and restricted employee spaces. Even a seemingly minor change to a wall, ceiling, electrical circuit, or doorway can interfere with equipment that protects the bank.

The national banking system is supported by a complex framework of financial institutions, regulators, and security standards. An overview of banking in the United States demonstrates how deeply regulated and operationally important these institutions are.

A contractor without bank renovation experience may approach the property like an ordinary commercial building. That creates the possibility of security weaknesses, interrupted services, incorrect material selection, and expensive corrective work.

An experienced contractor evaluates how every phase of construction affects the bank’s daily operations. This includes identifying restricted work zones, protecting customer information, controlling worker access, coordinating inspections, and maintaining secure separation between construction areas and occupied banking areas.

The Wrong Contractor Can Create Serious Security Risks 🚨

Physical security is one of the most important considerations during a bank renovation. Construction temporarily changes the normal environment of the branch. Walls may be opened, cameras may be relocated, entrances may be redirected, and employees may need to work in temporary spaces.

These changes can create vulnerabilities when they are not carefully controlled.

The Office of the Comptroller of the Currency’s guidance on bank premises and equipment addresses the importance of managing risks associated with banking facilities, equipment, security devices, operations, and reputation. These considerations make contractor selection a risk-management decision rather than simply a construction decision.

Construction workers and subcontractors may require access to areas that are normally closed to the public. The bank must know who is entering the building, where each person is working, and what equipment or information may be nearby.

A qualified general contractor can establish controlled entry procedures, maintain worker records, coordinate identification requirements, and ensure subcontractors stay within approved areas. The contractor can also schedule work involving alarms, cameras, doors, vault-related components, and access-control systems with the appropriate security professionals.

Without these safeguards, a renovation can unintentionally expose restricted spaces, confidential materials, or critical building systems.

Third-Party Risk Extends to Contractors and Subcontractors 🛡️

Banks carefully evaluate outside vendors because third-party relationships can create operational, compliance, security, and reputational risks. A general contractor becomes an important third party as soon as the company and its subcontractors enter the property.

The Federal Deposit Insurance Corporation’s resources on third-party relationships emphasize a risk-based approach to managing outside service providers. Although a construction company is not performing financial transactions, its workers may still have physical access to sensitive facilities and essential infrastructure.

The general contractor should therefore be prepared to provide insurance documentation, licensing information, references, safety records, project schedules, subcontractor details, and clearly defined procedures for accessing the property.

Hiring the lowest bidder without conducting proper due diligence can expose the institution to avoidable problems. An inexperienced contractor may hire poorly vetted subcontractors, fail to supervise the jobsite, ignore security procedures, or make unauthorized changes.

Banks searching for a General Contractor Near Me in Central Florida should prioritize commercial experience, communication, security awareness, project management, and familiarity with occupied facilities.

Construction Delays Can Interrupt Banking Operations ⏱️

A delayed residential remodeling project is frustrating. A delayed bank renovation can interfere with customer transactions, employee productivity, lending appointments, drive-through services, ATM access, and daily cash-handling procedures.

Banks often remain open during renovations. This requires carefully phased construction that allows customers and employees to move safely through the building while work continues in designated areas.

A qualified general contractor creates a schedule that accounts for demolition, material delivery, inspections, electrical work, technology installation, security coordination, and final testing. Work that creates excessive noise, dust, vibration, or temporary service interruptions may need to occur after hours or during periods of lower customer activity.

The contractor must also develop contingency plans. Central Florida construction projects can be affected by severe weather, supply delays, permitting requirements, labor availability, and unexpected conditions discovered behind walls or above ceilings.

A poorly managed schedule can force the bank to close portions of a branch longer than expected. It can also increase labor costs, disrupt appointments, frustrate customers, and create confusion among employees.

Experienced project management keeps the renovation organized and allows bank leadership to prepare for each phase before it begins.

Florida Banking Oversight Makes Compliance Essential 📋

Financial institutions operating in Florida must comply with applicable state and federal requirements. The Florida Office of Financial Regulation charters, licenses, examines, and regulates state-chartered financial institutions.

Construction itself is also governed by building codes, accessibility standards, fire-safety requirements, permitting rules, zoning restrictions, and local inspection procedures. Depending on the scope of work, a project may require architectural plans, engineering documentation, electrical permits, mechanical permits, plumbing permits, fire-system review, and final occupancy approval.

A contractor unfamiliar with these requirements can create delays before construction begins or cause failed inspections after work is completed.

Compliance problems may arise from incorrect doorway clearances, inaccessible service counters, improper ramps, inadequate emergency exits, unapproved electrical modifications, insufficient fire protection, or changes that were not included in permitted plans.

An experienced Central Florida general contractor coordinates with architects, engineers, inspectors, security vendors, and bank representatives to keep the project aligned with approved documents. This coordinated approach reduces the likelihood of stop-work orders, failed inspections, expensive corrections, and delayed reopening.

Modern Banks Depend on Technology Infrastructure 💻

Today’s bank branch is also a technology center. Employees rely on secure networks, communication systems, transaction equipment, digital displays, surveillance devices, access controls, and specialized banking software.

Renovation work can affect this technology even when the construction appears unrelated. Cutting into a wall may damage hidden wiring. Ceiling work may interfere with cameras or wireless equipment. Electrical changes can affect servers, teller stations, ATMs, alarms, and backup systems.

The Federal Reserve Bank of Atlanta serves the Sixth Federal Reserve District, which includes Florida, and works to support a stable, secure, and efficient financial system. The importance of that system is reflected at the branch level, where physical facilities and technology must work together reliably.

A qualified contractor coordinates construction activities with the bank’s information technology professionals and security providers. Before demolition begins, the team can identify important cables, electrical circuits, equipment locations, backup power requirements, and areas where work must be restricted.

This coordination protects expensive systems and reduces the possibility of downtime. It also ensures that newly renovated areas have the power, connectivity, ventilation, and physical protection required for future banking technology.

Central Florida’s Growth Is Changing the Banking Environment 🌴

Central Florida continues to attract residents, entrepreneurs, technology companies, professional service firms, and expanding corporations. This growth creates opportunities for banks, but it also increases competition.

The Orlando Economic Partnership’s financial technology resources highlight the region’s connection to financial technology, technical talent, and companies supporting the banking industry. As customer expectations change, banks must provide environments that combine personal service with digital convenience.

Older branches may need updated teller areas, private consultation rooms, collaborative workspaces, self-service banking technology, improved lighting, modern finishes, and more welcoming entrances.

A well-planned renovation can help a traditional branch feel more accessible without sacrificing security. Customers should be able to enter the building, understand where to go, complete transactions efficiently, and meet privately with banking professionals.

The wrong contractor may focus only on appearance. The right contractor considers appearance, security, workflow, customer privacy, accessibility, durability, and long-term maintenance.

A Bank’s Appearance Influences Customer Confidence ✨

Customers place enormous trust in financial institutions. They expect banks to protect their money, information, and personal financial details. The physical condition of a branch contributes to that perception of reliability.

Damaged flooring, poor lighting, stained ceilings, outdated service areas, temporary repairs, and unfinished construction can make customers feel uncertain. Even when banking operations remain secure, a neglected or poorly renovated building may suggest a lack of attention to detail.

A professionally completed renovation communicates stability, organization, and competence. Clean finishes, clear signage, private meeting areas, comfortable waiting spaces, and modern technology help customers feel confident in the institution.

Industry resources such as Florida Banking Magazine and BankNotes help financial professionals remain informed about developments affecting Florida’s banking industry. As banks respond to changing customer behavior and economic conditions, their physical branches remain an important part of their public identity.

A renovation should strengthen that identity rather than create an inconsistent or low-quality appearance.

Poor Workmanship Creates Long-Term Financial Costs 💰

A low construction estimate can become expensive when the work is not completed correctly. Poor workmanship may lead to water intrusion, flooring failures, electrical problems, damaged finishes, malfunctioning doors, inadequate ventilation, or recurring repairs.

Banks need durable materials because their facilities experience frequent customer traffic. Flooring, counters, doors, hardware, wall finishes, and restrooms must withstand daily use while maintaining a professional appearance.

An experienced contractor evaluates lifecycle cost rather than focusing only on the initial price. Higher-quality materials and proper installation can reduce maintenance expenses and extend the useful life of the renovation.

The contractor should also provide clear documentation regarding warranties, approved changes, inspections, materials, and completed work. This documentation gives bank leadership a reliable record of what was installed and who is responsible for addressing warranty issues.

Choosing a contractor solely because of the lowest bid may save money at the beginning while creating much larger costs later.

Local Experience Matters in Central Florida Construction 🌀

Central Florida presents construction challenges that contractors from other regions may not fully understand. High humidity, intense sunlight, heavy rain, tropical weather, and hurricane-related conditions can affect materials, roofing systems, exterior finishes, drainage, windows, doors, and construction schedules.

Local contractors are more likely to understand regional permitting procedures, inspection expectations, weather-resistant materials, and the practical demands of working during Florida’s rainy season.

Disaster preparedness is also important for financial institutions. Banks may need to restore services quickly following a major weather event because residents and businesses depend on access to financial resources.

A renovation provides an opportunity to examine roofing, drainage, exterior openings, backup power, emergency lighting, and other systems that can influence the building’s resilience.

The contractor should help the project team identify practical improvements while staying within the approved scope and budget.

The Right General Contractor Protects the Bank’s Reputation 🤝

A general contractor represents the bank while working on its property. Customers see construction vehicles, temporary barriers, workers, signage, and jobsite conditions. An organized project reflects positively on the institution, while a chaotic or unsafe project can create a negative impression.

The contractor should maintain clean work areas, professional conduct, clear walkways, visible safety measures, and consistent communication with bank management.

Strong communication is especially important when conditions change. Bank leadership should receive timely updates about schedule adjustments, discovered problems, material delays, inspections, and decisions that could affect cost or operations.

The right contractor does not simply complete construction tasks. The contractor becomes a partner responsible for protecting the bank’s facility, schedule, customers, employees, and reputation throughout the renovation.

Conclusion

Central Florida banks cannot afford to treat contractor selection as an ordinary purchasing decision. A renovation affects physical security, regulatory compliance, technology, employee productivity, customer confidence, and business continuity.

The wrong contractor can create hidden vulnerabilities, unexpected expenses, operational disruptions, failed inspections, and reputational damage. The right contractor brings commercial construction knowledge, careful supervision, transparent communication, local experience, and an understanding of the special responsibilities associated with working inside a financial institution.

As Central Florida continues to grow and banking technology continues to evolve, financial institutions must create branches that are secure, efficient, durable, accessible, and welcoming. A qualified general contractor helps transform that goal into a carefully managed construction project.

For a bank, high-quality construction is more than an improvement to the building. It is an investment in security, customer trust, operational stability, and the future of the institution. 🏦

The Secret Reason Dallas Banks Need Better Interior Design to Win Customer Trust

Banking News for Commercial Interior Design Dallas

Banks have always been built on trust. Customers trust banks with their deposits, their business accounts, their home loans, their retirement planning, and the financial decisions that shape their futures. But in Dallas, where business competition is strong and financial institutions are constantly working to stand out, trust is not created by services alone. It is also created the moment someone walks through the front door.

A bank’s interior design says something before a teller, loan officer, or branch manager ever speaks. It tells customers whether the bank feels stable, modern, organized, secure, professional, and welcoming. It also tells business owners, investors, and high-value clients whether this is a financial institution that understands details.

That is the secret reason Dallas banks need better interior design to win customer trust. The space itself becomes part of the brand experience. A well-designed bank does more than look attractive. It reduces uncertainty, improves comfort, strengthens credibility, supports employee efficiency, and helps customers feel confident about where they are placing their money.

In a financial market connected to the Federal Reserve Bank of Dallas, regional economic movement, commercial development, and changing customer expectations, banks cannot afford to treat interior design as a decoration project. It is a business strategy.

First Impressions Matter More in Banking Than Most Industries

When customers enter a restaurant, retail store, hotel, or office, they make quick judgments about quality. In banking, those judgments carry even more weight because the relationship involves money, privacy, and long-term financial security.

A dated lobby, poor lighting, worn furniture, confusing floor layout, or cold waiting area can quietly create doubt. Customers may not say it out loud, but they feel it. They wonder whether the bank is keeping up. They wonder whether the institution is detail-oriented. They wonder whether the customer experience matters.

That first impression becomes even more important in Dallas because customers have options. From national banks to regional institutions, credit unions, private banking offices, and digital-first financial services, people are surrounded by choices. A branch that feels outdated can make a bank seem behind, even if its services are excellent.

Better design helps remove that friction. Clean lines, comfortable seating, intentional lighting, clear signage, secure consultation areas, and a professional color palette can immediately tell customers, “You are in the right place.” That emotional reassurance matters.

A Dallas bank does not need to look flashy. In fact, most banks should avoid looking trendy in a way that feels temporary. The goal is to create a space that feels established, trustworthy, calm, and current.

Trust Is Built Through Comfort, Security, and Clarity

Interior design in a bank has to do more than impress people. It has to guide them. Customers should know where to go, where to wait, how to meet with someone privately, and how to complete their visit without confusion.

A strong bank layout creates clarity. Teller areas should be easy to identify. Private offices should feel accessible but protected. Waiting spaces should be comfortable without feeling casual. Digital banking stations, ATMs, and customer support areas should be positioned in ways that feel intuitive and safe.

Security is also part of the design experience. Customers do not want a branch that feels locked down like a fortress, but they also do not want a space that feels loose or exposed. The right design balances openness and protection.

This is especially important for financial conversations. A customer applying for a mortgage, opening a business account, discussing estate planning, or resolving fraud concerns does not want to feel overheard. Private consultation rooms, sound-conscious materials, and smart spatial planning can help customers feel respected.

That feeling of privacy directly supports trust. When a customer believes a bank has thought carefully about their comfort and confidentiality, the bank earns credibility.

For Dallas institutions considering branch updates, working with a professional team that understands Commercial Interior Design Dallas can help connect brand identity, customer experience, security, and functionality into one cohesive space.

Dallas Banking Is Competitive, and the Branch Still Matters

Digital banking has changed customer behavior, but it has not erased the importance of physical branches. Many customers may deposit checks, transfer funds, or monitor accounts online, but they still visit branches for important decisions.

Business owners still want to sit across from someone when they are discussing lending, cash management, expansion, or commercial real estate financing. Families still want guidance when they are planning major purchases. Older customers may still prefer in-person service. New customers often want reassurance before opening accounts or moving money.

The Dallas Fed Banking and Finance section regularly tracks financial performance, lending, deposits, and other banking issues that affect institutions across the region. That kind of economic environment reinforces how important it is for banks to remain relevant, visible, and trusted in their local markets.

A bank branch is no longer just a transaction center. It is a relationship center. That means the design needs to support conversations, education, advisory services, and long-term customer loyalty.

The best bank interiors make customers feel like they are entering a place of expertise. They create a setting where the customer experience feels personal, not mechanical. That matters in a city like Dallas, where business relationships are often built through professionalism, confidence, and reputation.

Interior Design Helps Banks Serve Business Clients Better

Dallas has a strong business culture, and many banks compete for commercial clients, entrepreneurs, real estate professionals, medical practices, law firms, construction companies, and local corporations. These clients often choose banks based on service, speed, lending strength, relationships, and confidence.

When a business owner walks into a bank, the physical environment can support or weaken the bank’s message. If the branch feels cluttered, outdated, or poorly organized, it may not match the level of professionalism the bank claims to offer. If the space feels polished, efficient, and well-planned, it reinforces the idea that the bank understands business.

Commercial clients also value privacy. They may be discussing payroll, expansion plans, credit lines, deposits, or sensitive financial details. A better-designed bank can include private meeting rooms, executive-style consultation spaces, and areas designed specifically for business banking conversations.

This is where design becomes a revenue-supporting tool. It helps relationship managers have better conversations. It gives business clients a more professional experience. It makes the bank feel capable of handling serious financial needs.

A Dallas bank that wants to attract stronger commercial relationships should not overlook how its branch looks and feels. Business clients notice details because they run businesses themselves.

A Better Bank Interior Can Improve Employee Performance

Customer trust is not only shaped by what customers see. It is also shaped by how employees perform inside the space.

Poor interior design can make employees less efficient. If workstations are awkward, storage is limited, lighting is harsh, customer flow is confusing, or private meeting areas are hard to access, staff members have to work around the building instead of being supported by it.

Better design helps employees serve customers faster and more confidently. It can reduce bottlenecks, improve communication, create better visibility, and support smoother transitions between teller service, advisory meetings, loan discussions, and management support.

The Eleventh District Banking Trends report from the Dallas Fed tracks important regional banking conditions, including profitability, loans, deposits, and asset quality. In an environment where banks are watching performance carefully, operational efficiency matters. Interior design may not be the first thing leaders think of when improving branch performance, but it can influence daily productivity in practical ways.

Employees who work in a well-designed environment are also more likely to feel pride in the brand. That pride can carry into customer service. A confident, comfortable, professional employee helps customers feel more confident too.

Modern Bank Design Must Balance Technology and Human Connection

Today’s customers expect technology, but they still want people when the stakes are high. That creates a challenge for banks. The branch must feel modern without becoming cold. It must support digital tools without making customers feel abandoned.

A strong interior design plan can make technology feel natural. Digital check-in stations, self-service kiosks, interactive screens, ATM areas, and video banking tools can be integrated into the space without making the branch feel like a machine.

At the same time, the design should preserve human warmth. Comfortable seating, welcoming materials, natural light, friendly reception points, and private offices all help customers feel seen.

The FDIC Bank Data & Statistics resources show how much banking decisions are driven by measurable performance, deposits, financial reports, and market data. But customer trust is not built by numbers alone. It is built by the experience surrounding those numbers.

A modern Dallas bank branch should communicate both innovation and reliability. Customers should feel that the bank is current enough to handle today’s technology but grounded enough to protect long-term relationships.

Design Can Make a Bank Feel More Local and More Connected to Dallas

Many banks want to feel personal, but their interiors often feel generic. A branch could be in Dallas, Denver, Phoenix, or Atlanta and look exactly the same. That can be a missed opportunity.

Dallas has its own business personality. It is bold, polished, entrepreneurial, and relationship-driven. A bank that reflects the local market can feel more connected to the people it serves.

That does not mean filling the lobby with clichés. It means making thoughtful design choices that reflect the surrounding community. Local artwork, regional materials, Dallas-inspired architectural details, and design elements that feel connected to North Texas can help a bank feel less corporate and more rooted.

Customers want financial strength, but they also want to feel known. A Dallas bank that looks and feels connected to the local market can create a stronger emotional bond with customers.

The FDIC Summary of Deposits Annual Survey highlights how branch office deposits remain an important part of understanding banking presence and market position. Physical locations still represent visibility, accessibility, and trust in a community.

A better-designed branch can turn that physical presence into a stronger brand advantage.

Outdated Design Can Quietly Damage a Bank’s Reputation

The most dangerous design problem is not always obvious. A bank may not look terrible. It may simply look tired.

That is enough to create doubt.

Old carpet, heavy furniture, faded walls, poor lighting, scratched counters, cramped offices, and outdated signage can send the wrong message. Customers may assume the bank is not investing in itself. If a bank does not appear to invest in its own environment, customers may wonder how forward-thinking it is with technology, service, lending, and security.

This matters even more when financial news, market shifts, and banking competition are constantly shaping public perception. Industry publications such as American Banker’s Texas banking news regularly cover banking performance, leadership, mergers, regulation, and regional financial developments. Customers may not follow every detail, but they do sense when the financial world is changing.

A bank branch that looks current helps reassure customers that the institution is moving with the times. It shows leadership, care, and confidence.

Better Interior Design Supports Brand Authority

For banks, brand authority is not just built through advertising. It is built through every customer interaction. The website, signage, staff, lobby, offices, meeting rooms, and even the waiting area all work together to shape perception.

A professional interior gives a bank stronger visual authority. It makes marketing claims feel real. If a bank says it offers premium service, the interior should feel premium. If it says it serves small businesses, the branch should be designed to welcome business conversations. If it promotes personal service, the space should feel warm and accessible.

The Office of the Comptroller of the Currency emphasizes the importance of supervision, safety, soundness, and compliance in the banking system. While interior design is not a replacement for strong banking fundamentals, it can help communicate the seriousness and professionalism customers expect from a financial institution.

Great design makes the brand believable.

Conclusion

The secret reason Dallas banks need better interior design to win customer trust is simple: customers judge the strength of a financial institution before they ever sit down for a conversation.

They judge it in the lobby. They judge it at the teller line. They judge it in the lighting, the seating, the privacy, the cleanliness, the signage, the offices, and the overall feeling of the space.

A better-designed bank does not just look nicer. It feels safer, more professional, more organized, more modern, and more trustworthy. It helps customers feel confident. It helps employees work better. It helps business clients take the institution seriously. It helps the bank’s brand match the level of service it wants to provide.

In a competitive Dallas banking market, trust is everything. Interior design is one of the most overlooked ways to build it.

Banks that invest in better spaces are not just updating their appearance. They are strengthening the customer relationship from the moment someone walks through the door.

Banking on Property Protection: How Large Acreage Vegetation Management in Mt. Lookout WV Supports Land Value, Loan Confidence, and Long-Term Investment

Banking News for Large Acreage Vegetation Management Mt. Lookout WV

For banks, lenders, property owners, and rural investors across West Virginia, land is more than open space. It is collateral, equity, opportunity, and long-term financial security. Whether a property is tied to agriculture, commercial development, family land, estate planning, or future resale value, the condition of that land can affect how confidently people borrow, lend, insure, invest, and grow.

That is why property protection should not only be viewed as a maintenance issue. It should also be viewed as a financial strategy. In communities like Mt. Lookout, WV, where acreage, wooded terrain, rural access, and long-term property ownership often play a major role in local wealth, large acreage vegetation management can help support land value, reduce risk, and improve the overall condition of a property.

For a West Virginia banking audience, this matters because strong land stewardship can contribute to stronger property files, better borrower confidence, and a healthier local economy. 🏦

Why Land Condition Matters in Rural Banking

Banks understand that land is not just dirt, trees, and boundaries on a survey. Land often represents one of the largest assets a person, family, business, or estate may own. In rural and semi-rural areas, property value is closely tied to usability, access, drainage, appearance, safety, and long-term maintenance.

When land becomes overgrown, neglected, or difficult to access, it can create concerns that go beyond curb appeal. Thick vegetation can hide drainage issues, fallen trees, damaged fencing, unsafe access roads, erosion problems, abandoned debris, and areas that may be difficult to inspect. For lenders, appraisers, insurance companies, and buyers, uncertainty can affect confidence.

That is why services such as Large Acreage Vegetation Management Mt. Lookout WV can play an important role in helping landowners protect their property’s practical and financial value. Proper vegetation management helps make acreage easier to evaluate, safer to access, and more useful for future planning.

In a state like West Virginia, where hillsides, forests, farmland, and rural properties are part of the landscape, land care is part of responsible ownership. Property that is maintained with intention often tells a stronger story to banks, buyers, heirs, developers, and community partners.

The Connection Between Vegetation Management and Property Value

Property value is influenced by more than location. Land that is usable, accessible, and well maintained may be more attractive to potential buyers, developers, agricultural users, and financial institutions. When acreage is overgrown, a buyer may see uncertainty. When acreage is managed, a buyer may see possibility.

Large acreage vegetation management can help open up usable areas, improve visibility, support better site access, and make the land easier to walk, review, and plan around. This can be especially valuable for owners who are preparing to refinance, sell, transfer ownership, expand operations, or use land as part of a broader investment strategy.

From a banking perspective, this matters because confidence matters. A lender reviewing property connected to a loan wants clarity. An appraiser needs reasonable access. A borrower wants to show that the property is being cared for. A future buyer wants to understand what they are purchasing. Vegetation management does not replace appraisals, surveys, inspections, or financial due diligence, but it can support a cleaner, more organized property picture.

The West Virginia Bankers Association represents banking institutions throughout the state, and one of the larger themes in community banking is local understanding. West Virginia banks often know the land, the industries, the families, and the economic realities behind rural property ownership. That local awareness makes property condition even more important because land is not just an asset on paper. It is part of the community’s financial foundation.

How Better Land Management Can Support Loan Confidence

Loan confidence is built on many things, including credit strength, income, repayment ability, collateral, documentation, and risk management. When land is part of the lending conversation, property condition can become one more piece of the overall picture.

A well-maintained large acreage property may help reduce unknowns. Clear access points, managed growth, visible boundaries, and improved usability can make it easier for landowners and lenders to understand the property’s current condition. This can be helpful for agricultural loans, rural business financing, real estate investment, land improvement loans, construction planning, and refinancing conversations.

The West Virginia Division of Financial Institutions helps oversee state-chartered and licensed financial institutions, and its mission centers on safe, fair, and necessary financial products and services for the public. That kind of financial environment depends on trust, documentation, and responsible decision-making. While vegetation management is not a banking regulation, it fits into the broader idea of protecting property, reducing preventable issues, and helping landowners act with responsibility.

For landowners, this means thinking ahead. Instead of waiting until a property becomes hard to access or difficult to evaluate, proactive vegetation management can help keep the land in a stronger position. For banks, this can support a more confident conversation when property is tied to a financial decision.

Reducing Risk Before It Becomes Expensive

One of the biggest financial benefits of land maintenance is prevention. Overgrown land can create problems that are more costly to fix later. Unmanaged vegetation may contribute to blocked access roads, drainage trouble, pest concerns, fallen limbs, wildfire fuel buildup in certain conditions, and hidden hazards that can create liability concerns.

For property owners, these problems can become expensive. For banks and lenders, they can create uncertainty when land is connected to collateral, estate management, foreclosure prevention, or long-term investment planning. The cleaner and more accessible a property is, the easier it can be to identify concerns before they become larger financial burdens.

In West Virginia, banking news often intersects with issues that affect the state’s economy, land use, energy, development, and community stability. The West Virginia State Treasurer’s Restricted Financial Institutions List is one example of how banking, state policy, and economic priorities can overlap. While that topic is separate from vegetation management, it shows how deeply financial decisions are connected to West Virginia’s land, industries, and long-term economic direction.

Landowners who take care of large acreage are also protecting something larger than a private property. They are helping maintain the quality and usefulness of land that may support homes, farms, business activity, recreation, timber, development, or generational wealth.

Why Banks Should Care About Property Stewardship

A bank does not have to own a piece of land to care about its condition. Banks are deeply connected to the health of local property markets. When land values are stable, borrowers are more confident. When borrowers are confident, they are more likely to invest. When property is maintained, communities often look stronger to residents, businesses, and future investors.

This is especially true in rural areas where property may stay in families for generations. A piece of land in Mt. Lookout may represent retirement planning, inheritance, business expansion, agricultural production, or a future home site. If that land is neglected, its usefulness can decline. If it is maintained, it may remain a stronger part of a family’s financial future.

The Federal Deposit Insurance Corporation has issued guidance connected to financial institutions and recovery efforts in West Virginia areas affected by hardship. This reflects an important truth: banks are not separate from local conditions. Weather, land, roads, property access, disaster recovery, and community stability can all influence the financial health of a region.

For banks serving West Virginia communities, encouraging responsible land stewardship can be part of a broader message about financial preparedness. It tells customers that protecting property is part of protecting wealth.

Large Acreage Vegetation Management as a Long-Term Investment

Many property owners think of vegetation management as an expense. A stronger way to view it is as an investment in usability, safety, access, and future opportunity. Just as a business invests in equipment, a homeowner invests in repairs, or a farmer invests in productivity, a landowner can invest in the condition of acreage.

Large acreage vegetation management can support long-term investment by helping landowners keep more of their property usable. It can improve access to remote areas, make it easier to plan future improvements, and help prevent the kind of neglect that can reduce buyer interest or increase cleanup costs later.

Financial news in West Virginia often highlights the relationship between banks, state priorities, and local industry. Reporting from West Virginia Public Broadcasting has covered banking issues tied to state financial policy and energy-related decisions. This matters because West Virginia’s economy has always been closely connected to land-based industries, rural ownership, and long-term resource planning.

When property owners manage large acreage wisely, they are helping preserve the financial usefulness of that land. They are also helping create stronger conditions for lending, investment, resale, development, and family planning.

What Property Owners Gain From Better Visibility and Access

Visibility is one of the most underrated parts of property protection. When land is overgrown, owners may not know what is happening across the full property. They may miss drainage issues, tree damage, erosion, unauthorized dumping, damaged fences, or areas that need repair. Banks, appraisers, and insurance representatives may also have a harder time reviewing the property.

Vegetation management can help open the land so owners can see what they have. That visibility can lead to smarter decisions. It can help owners prioritize improvements, identify risks, and plan with more confidence.

For buyers and borrowers, clear access can also build trust. A property that is easier to walk and review may feel more organized and better maintained. That feeling can influence how people think about value, risk, and future opportunity.

National banking coverage, including reporting from Reuters, has shown that West Virginia banking issues can attract attention beyond the state. This makes it even more important for local banks, property owners, and land investors to think carefully about how property, policy, lending, and long-term economic confidence all connect.

A Stronger Property Supports a Stronger Community

When land is cared for, communities benefit. Maintained acreage can support safer roadsides, clearer boundaries, improved access for emergency needs, better future development options, and stronger property appearance. It may also help reduce the burden on heirs or future buyers who would otherwise inherit years of neglected growth.

For a West Virginia bank website, this is a valuable message. Banking is not only about checking accounts, loans, and interest rates. It is about helping people make wise decisions with the resources they already have. Land is one of those resources.

A customer who owns acreage in Mt. Lookout may not immediately think about vegetation management when discussing property value or lending. But the connection is real. Better land condition can support better planning. Better planning can support stronger financial decisions. Stronger financial decisions can support healthier families, businesses, and communities.

Vegetation management is not just about clearing land. It is about protecting options. It helps landowners preserve access, reduce avoidable problems, and keep their property ready for what comes next. 🌿

Conclusion

Banking on property protection means understanding that land care and financial strength are connected. For large acreage owners in Mt. Lookout, WV, vegetation management can support land value, loan confidence, long-term investment, and responsible property stewardship.

When land is accessible, maintained, and easier to evaluate, it becomes more than a piece of property. It becomes a stronger financial asset. It can help support family wealth, rural investment, business opportunity, and community confidence.

For West Virginia banks, this topic belongs in the conversation because strong land supports strong lending, stronger borrowers, and stronger local economies. Large acreage vegetation management is not only a property maintenance service. It is a practical step toward protecting value, reducing risk, and building long-term confidence in the land people count on.

Banking on Safety: Why Women’s Concealed Clothing for Women Is Changing Everyday Protection

Banking News for Women’s Concealed Clothing for Women

Safety has become part of everyday decision-making. People think about it when they choose where to shop, where to park, which route to take home, how they manage their money, and how they move through public spaces. In the same way banking has evolved from a simple place to deposit money into a full system built around protection, access, convenience, and confidence, personal safety has also changed. Women are no longer looking for one-size-fits-all solutions. They want options that match their lifestyle, their responsibilities, their routines, and their sense of independence.

That is one reason Women’s Concealed Clothing for Women is becoming part of a bigger conversation about everyday protection. It is not just about clothing. It is about preparation, peace of mind, and the ability to move through daily life with more confidence. Whether a woman is commuting to work, running errands, traveling, attending events, or managing a busy family schedule, what she wears can support how safe, prepared, and comfortable she feels.

Banking news often focuses on risk, fraud prevention, consumer confidence, digital safety, and financial protection. Those same themes apply to personal protection in real life. A strong bank protects assets. A strong safety plan protects the person. The connection may seem unexpected at first, but both are built around the same idea: people want to feel secure in a world that keeps changing. 🛡️

Banking on Safety in a Changing World

Modern consumers are paying closer attention to safety than ever before. In banking, people read updates from trusted sources like Reuters Finance & Banking News to understand how financial institutions respond to market shifts, consumer risks, and policy changes. In daily life, women are also thinking about how they respond to uncertainty, especially when they are out in public, traveling alone, or balancing multiple responsibilities.

Everyday protection is no longer limited to alarms, cameras, or emergency contacts. It also includes practical choices that fit naturally into a woman’s routine. Clothing is one of those choices because it is used every single day. When clothing is designed with concealment, comfort, and accessibility in mind, it gives women another layer of preparedness without forcing them to sacrifice style or mobility.

Women’s concealed clothing has become more relevant because it meets a real need. Traditional concealment options often failed to consider women’s bodies, clothing preferences, movement, and daily activities. Many products were designed around men first, then adjusted later for women. That left many women feeling like they had to choose between safety and comfort. Modern concealed clothing helps close that gap by offering more thoughtful designs for real-life use.

Why Everyday Protection Is Becoming More Personal

Personal safety is deeply personal. Just as no two people manage their finances the exact same way, no two women approach safety in the exact same way. Some women want concealed clothing for travel. Some want it for long workdays. Some want it because they frequently walk through parking lots, attend events, or work in areas where they prefer to feel more prepared. Others simply want clothing that gives them options without drawing attention.

The banking industry understands the importance of personal choice. Consumers expect accounts, cards, mobile tools, fraud alerts, and security settings that fit their lifestyle. Trusted organizations such as the Federal Reserve News & Events page help people follow major updates that affect the financial system. In the same way, personal safety products are becoming more individualized because women want choices that fit their bodies, schedules, and comfort levels.

This shift matters because protection should not feel awkward, bulky, or impossible to use. A woman should not have to completely change how she dresses just to feel safer. She should be able to choose clothing that works with her life instead of against it. That is one of the biggest reasons concealed clothing designed specifically for women is gaining attention.

The Connection Between Financial Confidence and Personal Confidence

Banking is built on trust. People place their money into financial institutions because they expect security, accountability, and access when they need it. They follow resources like FDIC News because deposit insurance, banking stability, and consumer confidence all affect how safe people feel about their financial future.

Personal safety works in a similar way. Women want to feel like they have access to the tools they need when they need them. Confidence comes from preparation. It comes from knowing that a decision was made ahead of time, not in the middle of a stressful moment. Concealed clothing can help support that confidence by making safety feel more integrated into everyday life.

This does not mean every woman has the same safety plan. It means more women are recognizing that preparation can be quiet, practical, and personal. The right clothing can support daily movement, reduce discomfort, and help women feel less restricted. When a product is designed with a woman’s lifestyle in mind, it becomes more than apparel. It becomes part of how she protects her peace.

How Women’s Concealed Clothing Is Changing the Shopping Conversation

Shopping habits have changed across nearly every industry. People research before they buy. They compare features. They read reviews. They look for brands that understand their real needs. Banking news outlets such as American Banker regularly cover how consumer expectations, technology, and trust shape the financial world. Those same expectations are influencing how women shop for clothing related to safety.

Women are no longer satisfied with products that simply claim to be functional. They want clothing that feels good, looks good, and performs well. They want designs that do not make them feel obvious or uncomfortable. They want options that allow them to move through the day without constantly adjusting, hiding, or worrying.

That is why concealed clothing for women is gaining momentum. It brings together comfort, practicality, and confidence. It also acknowledges that women deserve products made specifically for them, not just modified versions of products originally created for men. When the shopping experience respects the customer’s real life, trust grows.

Banking News, Consumer Trust, and the Rise of Safety-Focused Products

Consumer trust is one of the strongest forces in both banking and retail. People want to know that the companies they rely on are credible, thoughtful, and transparent. The Associated Press Financial Services News covers financial services topics that affect consumers, institutions, and the economy. That kind of reporting helps people stay informed and make better decisions.

In the world of safety-focused clothing, trust is just as important. Women need to feel confident that the clothing they choose is designed with care. They want to understand how it fits, how it functions, and whether it can support their day-to-day needs. A product connected to personal protection must do more than look appealing. It must feel dependable.

This is where quality content also matters. A brand that educates customers, explains product purpose, and connects its message to broader consumer safety conversations can build stronger authority online. When an article includes relevant, trusted sources, it gives readers more context and helps search engines understand that the content is connected to credible industry themes.

Why Design Matters for Women’s Protection

The design of concealed clothing matters because women’s clothing is often more varied than men’s clothing. Women may wear fitted tops, leggings, dresses, jackets, workwear, casualwear, or layered outfits depending on the day. A concealed option that works for one outfit may not work for another. This is why thoughtful design is so important.

Good concealed clothing should consider movement, comfort, access, concealment, and confidence. It should not create unnecessary bulk or make the wearer feel restricted. It should support daily activity without constantly reminding the woman that she is wearing something for protection. The best designs are practical without being distracting.

This is similar to how modern banking tools are expected to work quietly in the background. Consumers want fraud monitoring, mobile access, alerts, and protections that support their lives without making every transaction feel difficult. Resources like the Consumer Financial Protection Bureau Newsroom highlight the importance of consumer protection in financial decisions. In personal safety, the same principle applies: protection should help people feel supported, not burdened.

Everyday Preparedness Without Losing Style

One of the reasons women’s concealed clothing is changing everyday protection is because it allows safety and style to exist together. For years, many women felt that safety gear was either too bulky, too tactical, or too obvious. That created a barrier. If a woman did not feel comfortable wearing something, she was less likely to use it consistently.

Today, women are looking for clothing that blends into real life. They want pieces that can work for errands, travel, work, school pickup, shopping, and daily routines. The goal is not to look different. The goal is to feel prepared while still feeling like yourself.

A strong personal safety product should not take away confidence. It should add to it. When women can wear concealed clothing that matches their lifestyle, they are more likely to feel calm, capable, and ready. That kind of confidence matters because safety is not only about emergency moments. It is also about how a woman feels before she ever leaves the house.

The Role of Information in Better Safety Decisions

In banking, informed decisions are stronger decisions. People learn about interest rates, account protections, fraud prevention, and consumer rights because money matters. The same is true for personal protection. Information helps women choose the right safety tools, understand their options, and avoid products that do not fit their needs.

The basic definition and history of a bank show how financial institutions have long been connected to trust, deposits, lending, and public confidence. That foundation of trust is also important when discussing safety-related clothing. Women want brands that are clear, helpful, and honest. They want explanations that make sense, not fear-based marketing that pressures them into a purchase.

Educational content can make a major difference. It can explain why concealed clothing is useful, how it fits into daily life, and why women-specific design matters. It can also help readers understand that personal protection is not about living in fear. It is about being prepared, thoughtful, and confident.

Why This Topic Belongs on a Banking Website

At first glance, women’s concealed clothing may seem unrelated to banking. But a banking website often speaks to people who care about security, planning, risk management, smart choices, and protecting what matters. Those values connect naturally to personal protection.

Banking is not only about money. It is about stability. It is about helping people feel more in control of their future. Articles that connect banking themes to everyday life can bring fresh value to readers. A topic like women’s concealed clothing gives a banking website a way to discuss safety from a broader perspective while still staying connected to protection, confidence, and smart decision-making.

This type of article can also help expand topical authority. By using trusted banking-related sources, the content builds a bridge between financial safety and personal safety. It gives readers something useful while also supporting stronger credibility signals for the website.

Conclusion

Banking on safety means more than protecting money. It means making smart choices that support confidence, stability, and peace of mind in everyday life. Women’s concealed clothing is changing the way protection fits into daily routines because it gives women practical options that respect their comfort, movement, and personal style.

Just as people rely on trusted banking systems to protect their financial future, women are looking for dependable ways to protect their personal peace. Concealed clothing designed for women helps make safety feel less complicated and more natural. It supports preparation without asking women to give up who they are or how they want to dress.

The rise of women’s concealed clothing shows that everyday protection is becoming more thoughtful, more personal, and more empowering. For a banking website, this topic offers a meaningful way to connect security, trust, and confidence in a way that speaks to modern readers. Safety is not only something people keep in an account. It is something they carry into every part of life. 🔐

Why Banking Facilities Are Paying More Attention to Commercial Doors Houston

Banking News for Commercial Doors Houston

Banking facilities are built around trust. Customers walk into a bank expecting more than financial service. They expect order, privacy, professionalism, safety, and a physical environment that feels secure from the moment they approach the building. In a city as large, active, and economically important as Houston, that expectation carries even more weight. Banks, credit unions, lending offices, investment branches, and financial service centers are not just places where transactions happen. They are high-responsibility environments where people, records, money, technology, and customer confidence must be protected every day. 🏦

That is one reason more banking facilities are paying closer attention to their exterior and interior doors. A commercial door is not just an entry point. It is part of a building’s first impression, security posture, traffic flow, accessibility, emergency planning, and long-term maintenance strategy. For banking properties in Houston, where growth, traffic, weather, and business expectations all play a role, the right doors can make a noticeable difference in how a facility operates.

Houston’s banking environment is connected to a much larger regional economy. The Federal Reserve Bank of Dallas Houston Branch serves southeast Texas and tracks key industries that shape the region, including energy, shipping, trade, and health care. Banking facilities serving this kind of market need buildings that are dependable, secure, and ready for daily use. That is why the conversation around Commercial Doors Houston has become more important for banking leaders, property managers, and facility teams who want their buildings to support both customer confidence and operational control.

Banking Facilities Depend on Strong First Impressions

The front entrance of a banking facility says something before a customer ever speaks to a teller, banker, loan officer, or manager. If the door looks worn, damaged, hard to open, poorly aligned, or outdated, it can quietly create doubt. Customers may not stop and think, “This door is a problem,” but they can feel when a building does not look cared for.

In banking, those small impressions matter. Financial institutions compete on trust, service, convenience, and credibility. The building needs to support that message. A clean, sturdy, properly functioning commercial door helps communicate professionalism. It shows that the facility is maintained, that the business pays attention to details, and that customers are entering a place that takes security and care seriously.

This is especially true in Houston, where banking locations may serve a wide range of customers, from small business owners and homeowners to commercial clients, investors, and high-traffic retail banking customers. A branch near a busy commercial district may experience constant daily use. A bank near growing residential areas may see steady foot traffic from families, retirees, and local professionals. A financial office serving business clients may need a more polished, executive feel. In every case, the door contributes to the experience.

Security Is a Major Reason Banks Are Looking at Door Quality

Banking facilities naturally have higher security expectations than many other commercial properties. While cameras, alarms, access control systems, lighting, and staff procedures all matter, the physical door system remains one of the most important parts of a secure building. A weak, damaged, or outdated door can create unnecessary risk.

Commercial doors used in banking environments may need to support controlled entry, restricted employee access, after-hours security, fire-rated areas, secure back rooms, equipment spaces, cash-handling areas, and private office zones. This means the door itself, the frame, the closer, the hinges, the lock hardware, and the access components all need to work together.

The Texas Department of Banking explains that its mission includes helping ensure a safe, sound, and competitive financial services system in Texas. While that mission focuses on the financial system itself, the same mindset applies at the facility level. Banks must think carefully about risk, reliability, and customer protection. A facility that handles sensitive customer interactions should not treat doors as an afterthought.

Security is also about consistency. A door that does not close all the way, drags on the floor, has a loose lock, or fails to latch properly can create a vulnerability. In a banking setting, those issues should be addressed quickly. The goal is not to create a building that feels intimidating. The goal is to create a building that feels safe, controlled, and professionally maintained.

Houston’s Growth Makes Facility Planning More Important

Houston is one of the most important business cities in the United States. Its economy includes energy, ports, medical institutions, construction, international trade, finance, and small business growth. According to the Wikipedia overview of Houston, the city is one of the largest in the country and serves as a major economic center. That level of activity creates constant demand for banking services.

As Houston continues to grow and shift, banks must think about how their facilities handle traffic, location demands, and customer expectations. Some branches may need upgrades because more people are coming through the doors. Others may need better commercial doors because the building is aging, the hardware is worn, or the location has changed in use over time.

A door that worked well years ago may no longer match the daily needs of the building. If a banking facility has more customers, longer operating hours, more employees, updated technology, or expanded services, the entry systems should keep up. Facility decisions must support the way the bank functions now, not just the way it operated when the building was first built.

Commercial Doors Support Customer Flow and Accessibility

Banking facilities must be easy to enter, navigate, and exit. Customers may include older adults, people with disabilities, parents with children, business owners carrying documents, and employees moving between public and restricted areas throughout the day. A commercial door that is too heavy, slow to close, difficult to open, or improperly adjusted can create frustration.

Accessibility is not only about compliance. It is about service. When a customer has trouble entering a building, that experience affects how they feel about the business. Banking already involves serious decisions and sometimes stressful conversations. The building should not add more friction.

The Americans with Disabilities Act provides important guidance around accessibility for public accommodations and commercial facilities. For banks, that means doors should be considered as part of the larger customer experience. Proper width, hardware, opening force, thresholds, closers, and automatic access options may all matter depending on the building.

Good commercial doors help customers move smoothly while still supporting security. That balance is important for banking facilities because they need to feel welcoming without losing control over access.

Weather and Durability Matter in Houston

Houston weather can be tough on commercial buildings. Heat, humidity, heavy rain, wind, and storm activity can all affect doors, frames, hardware, seals, and finishes. Banking facilities need exterior doors that can stand up to local conditions without constant problems.

When doors are exposed to Houston’s climate, low-quality materials or poor installation can lead to swelling, rust, corrosion, air gaps, water intrusion, misalignment, and hardware failure. These problems can affect security, energy efficiency, appearance, and customer comfort.

The National Weather Service Houston/Galveston office provides local weather information for the region, and any Houston business owner knows weather is part of facility planning. For banking properties, that planning should include durable door systems that can handle daily use and local environmental demands.

Durability also affects maintenance costs. A cheaper or poorly fitted door may seem acceptable at first, but repeated repairs, service calls, security concerns, and customer-facing appearance problems can make it more expensive over time. Banking facilities often benefit from investing in stronger commercial-grade doors and hardware because reliability matters every day.

Banks Need Doors That Work With Modern Access Control

Modern banking facilities often use access control systems to separate public areas from employee-only spaces. This can include card readers, keypads, electronic locks, automatic operators, restricted office entrances, IT rooms, cash-handling areas, and secure storage zones. A commercial door must be compatible with these systems.

The physical door is still the foundation. Even the best access technology cannot perform well if the door is warped, the frame is weak, the closer is failing, or the latch does not align. That is why banks should look at doors as part of the full security system, not as separate pieces.

The FDIC plays a major role in public confidence in the banking system, especially through deposit insurance and financial institution oversight. At the customer level, confidence also comes from what people see and experience inside a banking location. When secure doors, controlled access, professional hardware, and smooth building operation all work together, the facility feels more trustworthy.

Access control is not only for emergencies or high-risk areas. It also helps employees work more efficiently. Staff should be able to move through secure areas without fighting broken hardware or dealing with doors that stick, slam, or fail to close. In a busy banking environment, small door problems can slow down the day and create unnecessary distractions.

Interior Commercial Doors Matter Too

When people think about commercial doors, they often picture the front entrance. In banking facilities, interior doors can be just as important. Offices, meeting rooms, employee corridors, storage rooms, mechanical rooms, record areas, break rooms, and secure spaces all require the right doors for the right purpose.

A private lending office may need a door that supports confidentiality. A back-office area may need controlled access. A mechanical room may need a fire-rated door. A conference room may need a professional appearance that matches the rest of the facility. A restroom door may need durable hardware because of frequent use.

The Texas Department of Banking’s information on state-chartered banks and holding companies shows how closely financial institutions are connected to management practices, technology risks, compliance, and overall soundness. While that resource is focused on supervision, it reflects a larger truth: banking depends on systems working properly. Doors are part of the physical systems that support daily operations.

Interior commercial doors help divide space, protect privacy, manage employee movement, and create a more organized building. For banks, those details can influence both customer service and internal efficiency.

Fire Safety and Emergency Planning Cannot Be Ignored

Banking facilities must also think about safety beyond security. Fire-rated doors, emergency exits, panic hardware, proper closers, and clear pathways are essential in commercial buildings. A door that is blocked, damaged, or not closing properly can create serious safety concerns.

The National Fire Protection Association provides important information about fire and life safety standards. Banking facilities should make sure their doors support emergency planning and code requirements. This is especially important in buildings with multiple offices, secure rooms, employee-only spaces, and public customer areas.

A banking facility may have a beautiful lobby and modern technology, but if the door systems do not support safe evacuation and compartmentalization, the building has a serious weakness. Fire-rated doors should not be propped open. Exit hardware should function properly. Door closers should be adjusted correctly. Frames and seals should be maintained. These details may not be exciting, but they matter.

The Cost of Ignoring Door Problems Can Add Up

A damaged commercial door can create more than one problem. It can affect security, customer confidence, employee productivity, energy costs, accessibility, safety, and maintenance budgets. In a banking facility, small issues should not be allowed to turn into larger failures.

For example, a door that does not latch properly may require extra employee attention throughout the day. A front door that looks worn may weaken the building’s professional image. A back entrance with poor hardware may create a security concern. A door closer that slams can make customers uncomfortable and damage the frame over time. A poorly sealed exterior door can let in heat, moisture, and pests.

Banking facilities are expected to operate with discipline. Door maintenance should fit into that same mindset. Regular inspections, timely repairs, and thoughtful upgrades can help prevent bigger expenses later.

Conclusion

Banking facilities in Houston are paying more attention to commercial doors because the building itself plays a role in trust, security, service, and daily operations. A bank’s doors are not just construction materials. They are part of the customer experience, the safety plan, the security system, and the long-term performance of the property.

In a competitive and fast-moving city like Houston, banking facilities cannot afford to overlook the basics. Strong commercial doors help protect people, support access control, improve first impressions, handle heavy traffic, stand up to local weather, and create a more professional environment. From the front entrance to secure interior spaces, every door has a job to do.

For banks, credit unions, lending offices, and financial service facilities, paying attention to commercial doors is not just a maintenance decision. It is a business decision. The right door system helps the facility feel secure, organized, and dependable, which is exactly what customers expect from any place trusted with their money, information, and financial future. 🔐

How Mobile Fuel Delivery in Salt Lake City Helps a Bank Stay Prepared and Operational

Banking News for Mobile Fuel Delivery Salt Lake City

Banks carry a level of responsibility that reaches far beyond daily transactions. A bank supports families, local businesses, commercial accounts, lending operations, safe deposit services, ATM access, digital banking infrastructure, and the financial confidence of the communities it serves. In a growing market like Salt Lake City, where business activity, financial services, transportation demands, and customer expectations continue to evolve, preparation is not optional. It is part of the trust a bank builds every day.

For a bank, operational readiness means planning for more than routine business hours. It means thinking about backup power, facility access, fleet needs, ATM uptime, security systems, data continuity, and how employees and customers are supported during unexpected disruptions. Weather conditions, construction delays, emergency events, generator needs, and fuel supply interruptions can all affect a bank’s ability to remain open, responsive, and dependable.

That is why fuel planning matters. A bank may not seem like the first business people associate with fuel delivery, but banks rely on powered systems, transportation, emergency preparedness plans, vendor coordination, and facility management. When the goal is to stay prepared and operational, Mobile Fuel Delivery Salt Lake City can support the behind-the-scenes reliability that helps a bank serve its customers with confidence.

Salt Lake City Banks Operate in a Growing Financial Market

Salt Lake City is an important financial and business center in the Intermountain West. The city has a strong commercial base, a growing downtown, expanding business districts, and a financial services environment that supports both local and regional economic activity. The presence of the Federal Reserve Bank of San Francisco Salt Lake City Branch reinforces the city’s role in the broader financial system and highlights the importance of dependable banking operations in the region.

For banks, growth creates opportunity, but it also increases the need for preparation. More customers, more commercial accounts, more digital transactions, and more branch activity mean there is less room for avoidable delays. A bank has to think ahead about how it will maintain operations when normal conditions are interrupted. That includes having a plan for fuel-dependent systems such as generators, maintenance vehicles, service fleets, security support, and vendor operations.

Salt Lake City’s financial environment is also tied closely to statewide regulation and oversight. The Utah Department of Financial Institutions provides information connected to banks, credit unions, industrial banks, trust companies, and other financial institutions operating in Utah. This type of financial infrastructure reflects how important stability, compliance, and continuity are for institutions that handle money, credit, lending, and customer confidence.

A bank does not have the luxury of appearing unprepared. Customers expect access, answers, and security. Businesses expect deposits, payroll support, lending communication, and account services to continue as smoothly as possible. Mobile fuel delivery helps support that readiness by reducing one more operational risk.

Preparedness Helps Protect Customer Trust

Trust is one of the most valuable assets a bank has. Customers choose a financial institution because they believe their money, records, transactions, and financial goals will be handled carefully. That trust is strengthened when a bank is visibly organized, responsive, and steady during normal business days as well as during unexpected events.

Fuel planning plays a role in that trust because many essential banking systems depend on reliable power and transportation. Backup generators may be needed to support security systems, lighting, computer networks, HVAC systems, ATM access, and communication tools. Company vehicles or service vehicles may be needed for facility checks, branch support, courier needs, or emergency response. If fuel is not available when needed, small issues can quickly create larger disruptions.

For banks with multiple branches or facility responsibilities, mobile fuel delivery can help simplify readiness. Instead of sending employees or contractors away from the property to refuel vehicles or equipment, fuel can be delivered directly where it is needed. This helps save time, reduce disruption, and keep key people focused on the operation of the bank.

Preparedness is especially important in a city where financial news, business growth, and institutional activity continue to matter. Resources such as the Utah Department of Financial Institutions News show how active the financial services sector is across the state. Banks that take operational planning seriously are better positioned to serve customers, protect relationships, and keep daily functions moving.

Backup Power Planning Matters for Banks

A power outage can be inconvenient for many businesses, but for a bank, it can affect security, access, communication, and customer service. Even if a bank has strong digital systems, the physical branch still matters. Customers may need in-person help. Employees may need access to internal platforms. Security systems must remain active. ATMs, lighting, alarms, cameras, and controlled entry systems all depend on reliable power.

Generators are an important part of many emergency preparedness plans, but a generator is only useful if it has enough fuel. Mobile fuel delivery allows a bank to include generator fueling as part of a larger continuity plan. Instead of waiting until fuel levels become a concern, a bank can coordinate delivery in advance or arrange service when conditions require it.

This is especially useful during severe weather, regional disruptions, construction-related issues, or unexpected demand. If roads are busy, fuel stations are crowded, or employees are focused on customers, direct fuel delivery can reduce unnecessary stress. It gives facilities teams and leadership one less thing to chase down.

The Federal Reserve Bank of San Francisco’s Utah region shows how Utah is connected to a larger financial network. While local banks operate independently, the banking environment depends on reliability at every level. Continuity planning is not just a corporate concern. It is a local service concern, a customer confidence concern, and a community support concern.

Mobile Fuel Delivery Supports Bank Fleets and Facility Teams

Banks often have more moving parts than customers see. Behind the teller windows, lending desks, drive-through lanes, and customer service offices, there may be facility managers, maintenance teams, security vendors, courier services, armored transport coordination, branch support staff, and executive operations. Many of these functions depend on vehicles, equipment, or fuel-supported systems.

For a bank that manages multiple locations, mobile fuel delivery can make fleet coordination more efficient. Vehicles can be fueled on-site, which reduces downtime and avoids unnecessary trips to fuel stations. This can be helpful for banks with service vehicles, maintenance vehicles, company trucks, or other transportation needs connected to branch operations.

It can also support scheduled maintenance. Fuel delivery can be planned around business hours, facility needs, or operational schedules. A bank can avoid pulling staff away from higher-value responsibilities and reduce the chance of delays caused by low fuel levels.

This type of planning fits well with the disciplined approach banks already use in other areas. Banks track risk, review procedures, maintain compliance, and protect customer experience. Fuel delivery is another practical tool that supports those same priorities. It helps the bank stay organized, proactive, and less dependent on last-minute solutions.

Operational Continuity Helps Banks Serve Businesses

Many Salt Lake City businesses rely on banks for daily financial activity. Deposits, withdrawals, merchant services, business loans, credit lines, account support, and payroll-related transactions all matter. When a bank is disrupted, it can affect more than the branch itself. It can affect the businesses that depend on timely service and financial access.

Salt Lake City continues to be a strong place for business activity. The city’s economic development resources, including Doing Business in Salt Lake City, highlight the importance of workforce, infrastructure, and commercial growth in the area. As the business community grows, banks have to remain dependable partners for companies that need financial services to operate smoothly.

Mobile fuel delivery supports that dependability by helping banks prepare for interruptions before they affect customers. A branch with reliable backup power, fueled vehicles, and a clear fuel plan is better prepared to keep serving account holders, local companies, and commercial clients.

This matters because business banking is often relationship-driven. A company wants to know its bank is steady, accessible, and ready. Whether the bank is supporting a construction company, hotel, restaurant, trucking operation, healthcare provider, professional office, or local retailer, the expectation is the same. The bank must be prepared.

Fuel Delivery Can Strengthen Emergency Planning

Emergency planning is not only about major disasters. It also includes everyday interruptions that can affect a bank’s ability to function. A short power outage, a delayed fuel supply, a generator running longer than expected, or a vehicle that is not ready when needed can create avoidable problems. Mobile fuel delivery gives banks a practical way to strengthen emergency planning without creating unnecessary complexity.

This can be especially valuable for banks that maintain formal business continuity plans. Fuel delivery can be added to the list of vendor-supported services that help protect operations. The bank can know who to call, what fuel is needed, where delivery should happen, and how fueling fits into branch or facility procedures.

Financial institutions already understand the value of preparation. The banking industry is built around risk management, documentation, planning, and trust. Fuel delivery fits naturally into that mindset because it supports the physical side of continuity. Digital systems matter, but buildings, vehicles, backup power, employees, and customers still need dependable support.

Banking news in Utah continues to show the strength and movement of the financial sector. For example, Bank of Utah News shares updates connected to lending, community involvement, economic outlooks, and business activity. In a market where banks are active in community and business growth, operational reliability becomes even more important.

On-Site Fueling Helps Reduce Downtime

Downtime can cost a bank more than money. It can affect reputation, customer confidence, employee productivity, and business relationships. Even short interruptions can create frustration if customers are unable to access services or employees are unable to complete essential work.

On-site fueling helps reduce downtime because fuel comes to the bank’s location, equipment site, or vehicle area. This can be useful for generator fueling, fleet fueling, and planned operational support. Instead of reacting after fuel becomes a problem, the bank can schedule service in a way that supports normal operations.

This is especially helpful when a bank is preparing for extended hours, storm response, construction interruptions, special events, or periods of increased activity. It can also help if a branch is undergoing repairs, renovations, or site improvements and needs temporary power or equipment support.

The benefit is not only convenience. The benefit is control. A bank that controls its fuel planning has one more layer of protection against disruption. That can make a difference when customers are counting on the bank to be available.

Salt Lake City Banking Growth Makes Reliability Even More Important

Salt Lake City’s banking and financial landscape continues to develop. Regional banking activity, credit unions, industrial banks, and financial service companies all contribute to Utah’s broader economic identity. News coverage such as the Associated Press report on Redemption Bank reflects how banking developments in the Salt Lake City area can carry regional and national significance.

As the market grows, banks must continue investing in operational strength. Customers may notice friendly service, competitive lending options, convenient branches, and digital tools first. However, what protects those customer-facing services is the planning behind the scenes. Fuel readiness is part of that foundation.

A bank that prepares for power needs, fleet needs, and emergency response is better positioned to remain steady during unexpected conditions. It can keep employees safer, protect equipment, support customer access, and reduce preventable stress on leadership teams. This is not about overcomplicating operations. It is about making sure important basics are handled before they become urgent.

A Bank Can Use Fuel Delivery as Part of a Larger Continuity Strategy

Mobile fuel delivery should not be viewed as a standalone convenience. For a bank, it works best as part of a larger continuity strategy. That strategy may include backup power systems, cybersecurity planning, emergency communication procedures, vendor contact lists, facility inspections, employee response plans, and customer service protocols.

When fuel delivery is included in that strategy, the bank can create a more complete operational plan. It can identify which locations need support, which generators or vehicles require fuel, how often fuel levels should be checked, and who is responsible for coordinating delivery. This helps make the plan practical instead of theoretical.

Banks operate in a world where preparation is expected. Customers may never see the planning that happens behind the scenes, but they feel the results when a bank remains open, calm, and capable. They feel it when ATMs work, staff members can respond, facilities remain secure, and services continue.

Mobile fuel delivery helps create that kind of dependability. It gives banks a way to protect physical operations while continuing to focus on customers, compliance, lending, and financial service.

Conclusion

A bank in Salt Lake City has a responsibility to remain prepared, steady, and operational. Customers depend on the bank for access to money, financial guidance, business support, lending, deposits, and daily service. Local businesses depend on banks to help keep commerce moving. Employees depend on safe, functional facilities. Leadership depends on systems that can continue working when conditions change.

Mobile fuel delivery supports that responsibility by helping banks prepare for generator needs, fleet fueling, facility operations, emergency planning, and reduced downtime. It gives the bank a practical way to strengthen continuity while keeping staff focused on serving customers. In a growing financial market like Salt Lake City, that kind of preparation matters.

For a bank, fuel delivery is not just about convenience. It is about readiness, reliability, and protecting the trust customers place in the institution every day.

Why Banking Matters in Change Management for Chesapeake, VA Businesses

Banking News for Change Management Chesapeake VA

Change can look exciting from the outside, but inside a business it often feels like pressure. New systems, new leadership expectations, new compliance demands, new customer habits, and tighter margins can all force a company to move faster than it planned. That is especially true for businesses in Chesapeake, where growth, competition, and operational demands rarely stand still. For companies trying to adapt without losing momentum, Change Management Chesapeake VA is not just about communication plans or leadership meetings. It is also about financial structure, banking relationships, and access to the right kind of capital at the right time.

Banking matters in change management because most business change costs money before it produces results. A company may need to invest in software, payroll support, equipment, training, restructuring, or short-term working capital while the transition is still underway. When leadership treats banking like an afterthought, change initiatives can stall out halfway through. When leadership treats banking like a strategic partner, change becomes more stable, more realistic, and far more likely to succeed.

In Virginia, that idea is grounded in a real banking environment shaped by regulation, community banking, payments infrastructure, and ongoing industry movement. The Virginia State Corporation Commission’s Bureau of Financial Institutions oversees Virginia-chartered banks and related institutions, which shows how central banking remains to the state’s business framework.

Banking Gives Change a Financial Backbone

Every meaningful business change has a price tag attached to it. A company may be upgrading its accounting systems, shifting departments, hiring new leadership, expanding locations, or reworking internal controls. Even when those moves are smart, they create a temporary season where money goes out before efficiency comes back in. That is where banking becomes more than a place to hold deposits. It becomes part of the backbone that supports the transition.

A good banking relationship helps a business manage liquidity, credit access, treasury needs, payment timing, and risk visibility during uncertain seasons. Change management fails more often when businesses underestimate the operational cost of adjustment. A team may be emotionally ready for change, but if receivables lag, payroll tightens, or vendor obligations stack up, the strain shows up quickly. Banking helps leadership bridge that gap with better financial planning and more disciplined cash-flow support.

For Chesapeake businesses, this matters because local and regional companies do not change in a vacuum. They are changing while still serving customers, paying employees, and protecting vendor relationships. That means the financial side of change has to be as organized as the people side. Banking is what keeps the practical side of change from becoming chaotic.

Virginia’s Banking Climate Shows Why Strategy Matters

The broader Virginia banking climate reinforces this point. The Federal Reserve Bank of Richmond’s community banking resources focus directly on the role community banks play in the economy and the challenges they face while serving their communities. The Richmond Fed also highlights how payment services support currency flow, ACH activity, check processing, and settlement functions for financial institutions across the Fifth District, which includes Virginia.

That matters to Chesapeake businesses because change management is not only about internal culture. It is also about whether the financial systems around the business are dependable enough to support a transition. If a company is making changes to billing, payables, vendor workflows, or customer payment channels, it needs confidence in the banking structure behind those changes. Reliable payment systems, stable bank support, and informed financial guidance help reduce friction while the organization adjusts.

Business leaders who ignore the financial infrastructure behind change often end up solving the same problem twice. They roll out a new strategy, then discover the money movement, reporting cadence, or funding structure does not match the plan. Strong banking support helps prevent that mismatch.

Banking Helps Chesapeake Businesses Manage Risk During Transition

Risk increases during periods of change. Internal roles may shift. Decision-making may move to new people. Approval chains may be rewritten. Technology may replace manual steps that employees have relied on for years. All of that creates room for confusion, delay, and financial mistakes if the change is not grounded in clear controls.

This is one reason banking relationships matter so much. Banks often see patterns that businesses miss during change. They can help identify treasury gaps, fraud risks, credit pressure points, and timing issues tied to receivables and payables. That does not mean a bank runs the business. It means a strong bank relationship gives leadership another layer of discipline while the company is moving through disruption.

Virginia’s own regulatory environment reminds businesses that financial oversight is not optional. The Virginia SCC Weekly Bulletin regularly publishes current notices and information tied to the state’s financial institutions, which reflects how active and ongoing financial governance is in the Commonwealth.

For a Chesapeake business, that translates into a simple truth. Change without financial guardrails is expensive. Change with proper banking alignment is easier to control.

Change Management Works Better When Capital Is Timed Well

Many businesses do not fail because their change plan is wrong. They fail because the timing of the money is wrong. A company might know it needs to modernize operations, retrain staff, or invest in better reporting systems. The real problem is that the investment must happen before the payoff arrives. That is where banking can make the difference between delay and execution.

Lines of credit, operating accounts, treasury tools, payment services, and lending relationships can all play a role in smoothing that transition. Banking gives a business room to move instead of forcing it to make every change from pure cash reserves. That flexibility matters for Chesapeake businesses that want to grow responsibly while still protecting day-to-day operations.

This is especially relevant in a Virginia banking market that has been actively shifting. Virginia community bank mergers in 2025 included Atlantic Union Bankshares’ acquisition of Sandy Spring Bank, TowneBank’s acquisitions, and the Capital One-Discover combination, all of which show how much scale, reach, and integration activity has been shaping the state’s banking landscape.

When banks themselves are navigating consolidation and growth, businesses should understand that financial partnerships are evolving too. That is not bad news. It simply means business owners should pay attention and build relationships with banks that understand both expansion and transition.

Banking Supports Operational Confidence, Not Just Borrowing

A lot of business owners hear the word banking and immediately think loans. Borrowing matters, but it is only one part of the story. Good banking also supports forecasting, account structure, payment processing, fraud prevention, cash concentration, and financial visibility. Those things become even more valuable during change because the company needs accurate information fast.

A business that is changing successfully usually has better visibility into what money is doing every week, not just every quarter. It knows what is coming in, what is delayed, what has been committed, and where pressure is building. Banking tools help leadership see that more clearly. That clarity reduces panic. It helps business owners make better decisions when a transition becomes uncomfortable.

In Virginia, even national expansion activity points to how important banking access remains for communities and businesses. A recent Virginia Business report on Chase’s 2026 branch expansion in Virginia noted that JPMorgan Chase plans to add branches in Haymarket, Ashburn, and Fredericksburg as part of a broader expansion tied to access to banking services.

That kind of movement matters because it shows the market still values physical and relationship-based banking support even in a digital world. Chesapeake businesses should take the same lesson seriously. Relationship banking still matters when change is on the table.

The Right Banking Partner Helps Leadership Stay Focused

Leadership teams in the middle of change can get distracted by noise. Employees have questions. Customers notice adjustments. Vendors want clarity. Managers are learning new expectations. In that environment, leaders need fewer fires, not more. A strong banking relationship removes some friction by helping stabilize the financial side of the operation.

That support may show up in many ways. It may mean better cash management tools. It may mean more responsive credit conversations. It may mean stronger fraud controls while internal workflows are shifting. It may mean cleaner treasury reporting so leadership can see what is really happening. None of that replaces good leadership, but it gives leadership room to lead.

It also helps that banking policy continues to recognize the unique role of community banks. The FDIC reported that federal banking agencies proposed changes to the community bank leverage ratio framework that would reduce burden and provide community banks more flexibility while maintaining strong capital requirements. That proposal reflects continued attention to the realities community banks face in serving businesses and local markets. Businesses following developments like the FDIC’s community bank leverage ratio proposal can better understand how banking conditions may influence financing conversations and support options.

For Chesapeake businesses, this creates another layer of value. The stronger the banking ecosystem is, the more useful it can be during periods of transition.

Banking, Trust, and Business Reputation

Change management is not just internal. It affects how outside parties view the business. Vendors want confidence. Employees want stability. Customers want reliability. Investors and partners want signs that the company is moving with intention instead of reacting in panic.

That is where banking contributes to reputation. A well-banked business often looks more disciplined because it usually is more disciplined. It manages timing better. It handles obligations with more consistency. It communicates financial steadiness through action, not just messaging. During change, that steadiness becomes part of the company’s trust signal.

That is one reason why financial credibility matters so much in local markets like Chesapeake. Businesses here do not only compete on price. They compete on reliability. Banking support helps protect that reliability while leadership makes necessary changes.

Even well-known Virginia banking names reflect the importance of financial scale and credibility in the broader market. Capital One, headquartered in Virginia, remains one of the most visible examples of how banking presence can shape business confidence, market influence, and long-term growth. That does not mean every Chesapeake business needs a giant-bank strategy. It means financial alignment matters at every level, from local companies to nationally recognized institutions.

Conclusion

Why does banking matter in change management for Chesapeake, VA businesses. Because change is never only cultural, operational, or strategic. It is financial. Every transition depends on timing, liquidity, visibility, confidence, and control. A business can have the right vision and still struggle if the banking side is weak. It can also move through change far more effectively when the financial foundation is solid.

For Chesapeake business leaders, banking should not sit on the sidelines while change decisions are being made. It should be part of the conversation from the beginning. The right banking relationship can help support cash flow, reduce risk, improve decision-making, and keep change from becoming disorder. In a business environment where timing matters and trust matters even more, that kind of support is not optional. It is part of what makes change sustainable.